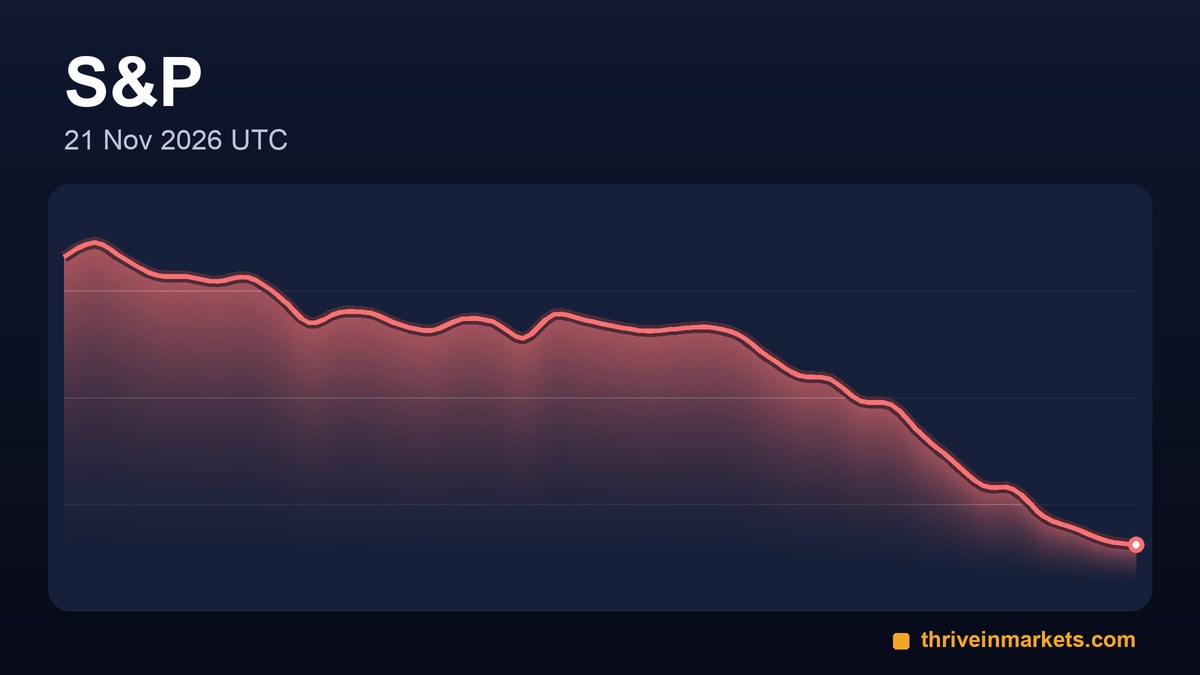
US stocks had their worst week since April 2025 as an AI selloff hit Nvidia and the whole chip sector, and Bitcoin slid under $60,000 with them. This is our look at the week from 15 to 21 November; the daily notes, such as Friday's evening review and Wednesday's Nvidia reaction, cover the day-by-day moves.
Prices as of 12:05 UTC on Saturday. Stock figures are Friday's close.
- The S&P 500 fell into a correction and the Nasdaq turned negative for the year because investors doubt AI spending will pay off soon.
- Nvidia lost about a quarter of its value in a week, even after a strong earnings report, as legal and export worries piled on.
- The Fed is widely expected to raise rates in December, which kept gold and Bitcoin under pressure.
Top Stock Stories of the Week
Nvidia has its worst week since 2008
Nvidia reported record quarterly revenue of $115.8 billion, more than double a year earlier, and gave a higher forecast. Shares still fell on Wednesday as investors focused on the search for a new CEO and China export risks.
On Friday Reuters reported that SEC enforcement staff are examining possible accounting issues at the company, and the stock fell 14% that day. For the week it lost about 23%, its worst since October 2008, wiping out roughly $1 trillion of market value. An SEC examination does not establish wrongdoing, and many close without action.
Anthropic's record debut fades
Anthropic priced the largest IPO ever, raising about $81 billion at $83 a share, and closed its first day on Thursday up 17%. That valued it at roughly $1.76 trillion. The pop did not last: the shares fell more than 10% on Friday as profit-taking hit chip and memory stocks.
The index damage
The S&P 500 lost 8.6% on the week to 6,910 and fell for a seventh straight day, which put it in a correction. The Nasdaq fell 10.0% to 22,618 and is now down for 2026, while the Dow lost 8.0%, its worst week since March 2020. The VIX volatility index nearly doubled on the week, to about 36.
- Good earnings were not enough: legal, political and valuation worries outweighed them.
- The selling spread to memory and power names such as Sandisk and Bloom Energy, which were among Friday's biggest losers.
Top Crypto Stories of the Week
Bitcoin breaks below $60,000
Bitcoin fell under $60,000 on Friday for the first time since July and trades near $58,000 on Saturday, about 9% lower than a week ago and about 20% down in November. It is on track for a seventh straight weekly loss, the longest run since 2022.
US spot Bitcoin ETFs lost about $1.25 billion on the week, and BlackRock's IBIT had a record one-day outflow of $541 million on Thursday. CoinGlass counted about $1.3 billion of leveraged bets wiped out in 24 hours, about 90% of them bets on higher prices.
Ether, XRP and Solana: ETF demand thins
Ether fell about 15% on the week to near $1,650, and Ether ETFs lost about $222 million. XRP funds saw about $11 million of net withdrawals. Solana funds took in under $5 million, which ended a run of about six weekly outflows, but nearly all of it arrived on Monday.
Dogecoin and other altcoins lead the fall
Dogecoin dropped about 16% to near 5 cents, its lowest since late 2023, and is heading for a seventh weekly loss. Solana is near $69, close to its June lows, and XRP is near 90 cents. Most large tokens fell more than Bitcoin as traders cut risk.
- Crypto is trading like a high-risk tech stock, falling when the Nasdaq falls.
- Record fund outflows show big investors stepping back, which leaves less support under prices.
Deals and Corporate News
Intuit agreed to sell Mailchimp to Bending Spoons for about $3.7 billion, far below the roughly $12 billion it paid in 2021, and plans to use the cash for share buybacks. Intuit's shares fell about 11% on Friday as it reported results.
Global Payments rose about 10% after Bloomberg reported that buyout firm GTCR is weighing a takeover valued near $50 billion including debt. No deal has been agreed.
- Buyout interest shows private equity still sees value in beaten-down companies, even in a falling market.
Regulatory and Macro
Minutes of the Fed's October meeting, released Wednesday, showed nearly all officials expect a quarter-point rate hike in December, and a couple were open to a bigger move. Governor Waller called for aggressive action and Governor Cook said policy is not restrictive enough. Futures put the odds of a December hike near 95%, and Chair Warsh has largely stopped giving rate guidance.
The stock rout pulled the 10-year Treasury yield down about 23 basis points on the week to 4.92%, while the dollar index stayed near a 19-month high. Gold fell about 9% to near $3,520, its worst week in eight months. October retail sales beat forecasts, but the Philadelphia and Empire State factory surveys missed by a wide margin. WTI crude is near $83 and on course for a third weekly loss.
- A December hike is the base case, so inflation data matter more than usual.
- Gold behaved like a risk asset this week, not a shelter.
Week Ahead: What to Watch
- Monday: US flash PMIs at 14:45 UTC and Fed's Williams at 21:00 UTC. Tokyo markets are closed for a holiday.
- Tuesday: Best Buy, Medtronic, Dell and Workday earnings, and US consumer confidence at 15:00 UTC.
- Wednesday: October core PCE inflation and the second Q3 GDP estimate at 13:30 UTC, then the Fed Beige Book at 19:00 UTC.
- Thursday and Friday: US markets are closed for Thanksgiving, then stocks close early at 18:00 UTC on Friday.
Scenarios to watch: core PCE is forecast at 3.2% a year, up from 3.1%. A hotter reading could add to rate hike bets and pressure stocks and Bitcoin, while a cooler one could ease it. Thin holiday trading can magnify moves either way.
- Wednesday's inflation and GDP data are the main test of the Fed hike story.
- Whether the AI selloff continues is the key question for stocks and crypto.
This is market commentary for information only, not investment advice. ThriveInMarkets is based in Cyprus and is not a licensed investment adviser.