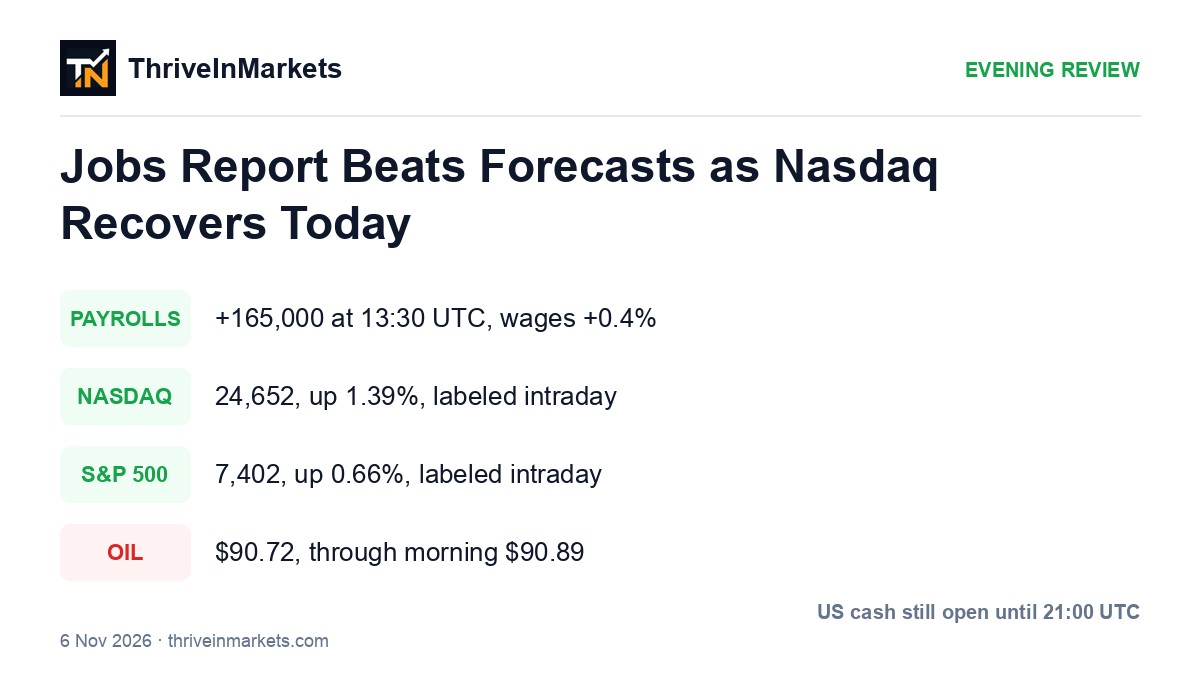
The October jobs report beat forecasts and the Nasdaq recovered today. As flagged in this morning's analysis, as of 20:00 UTC those S&P 500 and Nasdaq prints remain intraday, with US cash still open until 21:00 UTC.
The Close: Nasdaq Recovers While the S&P Holds Thursday's Low
The S&P 500 last printed about 7,402, up 0.66 percent from Thursday's 7,353.73 (Yahoo Finance 7,402.01 at 19:31 UTC; MarketWatch 7,401.90). Range 7,369.55 to 7,444.20. This morning's bullish reclaim at Thursday's 7,681.29 was not taken. The morning bearish reference at 7,350.35 was not taken (low 7,369.55). The Nasdaq Composite last printed about 24,652, up 1.39 percent from Thursday's 24,315 (Yahoo 24,652.23; MarketWatch 24,648.04). Range 24,508 to 24,824. The Dow last printed about 51,445, down 0.15 percent. Prints labeled intraday.
Chip stocks reversed Thursday's fade: AMD about 445.18 (+10.08 percent), Intel about 56.78 (+8.67 percent), Nvidia about 187.53 (+3.27 percent) (Yahoo Finance). The 10-year US yield last printed about 4.855 percent, up about 2 basis points from 4.837 percent. S&P bullish trigger: a hold through 7,444.20, then Thursday's 7,681.29. Bearish trigger: a fade through 7,369.55, then Thursday's 7,350.35.
- S&P about 7,402 (+0.66%), labeled intraday; Nasdaq about 24,652 (+1.39%); Dow about 51,445 (-0.15%)
- Morning 7,681.29 not taken (high 7,444.20); 7,350.35 not taken (low 7,369.55)
- AMD about $445.18 (+10.08%); Intel about $56.78 (+8.67%); Nvidia about $187.53 (+3.27%)
- S&P bullish trigger: hold 7,444.20 then 7,681.29; bearish: 7,369.55 then 7,350.35
Story of the Day: Payrolls Print 165,000 With Wages at 0.4 Percent
The Bureau of Labor Statistics printed October payrolls at +165,000 at 13:30 UTC, against this morning's FactSet median of +65,000 and Dow Jones at +59,000, after September's first print of +29,000. Unemployment fell to 4.1 percent against 4.2 percent seen. Average hourly earnings rose 0.4 percent on the month and 3.1 percent on the year, against 0.3 percent seen. August was revised to +186,000 and September to +60,000, a combined 84,000 higher (BLS). Guide: the jobs-report explainer.
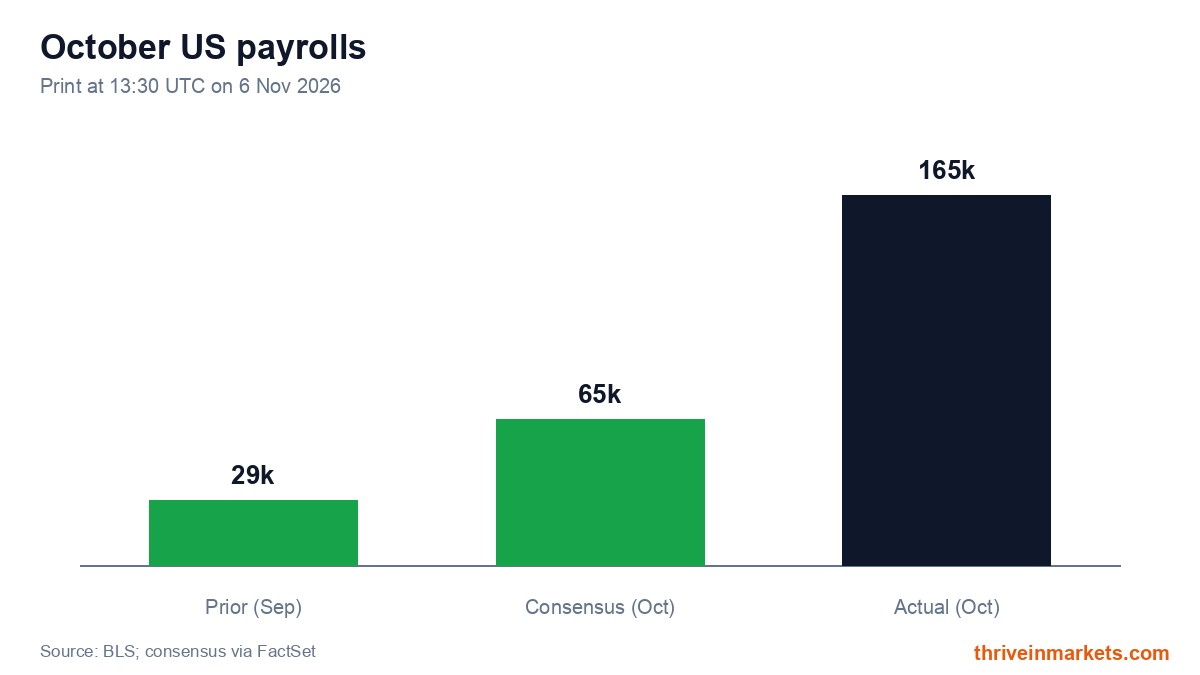
That is the mix this morning flagged: a print above 120,000 or wages at 0.4 percent would firm December hike odds, and both lines printed. CME FedWatch, via Reuters, sat near 78 percent for a December quarter-point increase, against this morning's 68 percent. University of Michigan preliminary November sentiment printed 51.0 at 15:00 UTC against 47.2 seen and October's final 48.0, with one-year inflation expectations at 4.3 percent against October's 4.7 percent. Canada lost 4,700 jobs against +16,100 seen, unemployment 6.7 percent against 6.5 percent (Statistics Canada). John Williams, speaking in Frankfurt before the 13:30 UTC print, said inflation is absolutely too high (Reuters).
- Payrolls +165,000 against +65,000 seen; unemployment 4.1%; wages +0.4% / +3.1%
- August and September revised up a combined 84,000; December hike odds about 78% against this morning's 68%
- Michigan sentiment 51.0 against 47.2 seen; Canada jobs -4,700, unemployment 6.7%
Oil Fades Through Morning Support After Tagging 92.53
West Texas Intermediate last printed about 90.72 dollars (Oilpriceapi at 19:30 UTC; Yahoo Finance 90.98, 0.29 percent apart). Session range 89.07 to 92.53 (MarketWatch, CoinDataFlow). This morning last printed about 91.57. The high tagged this morning's 92.53, then crude broke 90.89 and Thursday's 90.52 settle on the way to 89.07. Brent last printed about 98.53 dollars against this morning about 99.80. Oil bullish trigger: a reclaim of 90.89, then 92.53. Bearish trigger: a slip through 89.07.
Spot gold last printed about 4,064 dollars (Kitco 4,063.90 at 19:29 UTC, down 0.57 percent / 23.30 dollars, range 4,029.50 to 4,107.90). TradingView sat at 4,076.13, 0.30 percent apart. The morning bearish reference at 4,035.50 was taken (low 4,029.50). The morning bullish hold at 4,107.90 was not taken. Gold bullish trigger: a hold through 4,064, then 4,107.90. Bearish trigger: a slip through 4,029.50.
- WTI about $90.72 against this morning about $91.57; range $89.07 to $92.53
- Morning oil $92.53 taken then faded through $90.89 and Thursday $90.52
- Gold about $4,064 (Kitco, -0.57%); morning $4,035.50 taken (low $4,029.50)
- Oil bullish trigger: reclaim $90.89 then $92.53; bearish: $89.07
Crypto Check: Bitcoin Holds After Tagging Both Morning Levels
Bitcoin last printed about 75,704 dollars (TradingView). Kraken last printed 75,615.70, 0.12 percent apart. This morning last printed about 75,556. Today's Kraken range 74,790 to 76,300.70. The high tagged this morning's bullish reclaim at 76,300.70. The morning bearish references at 75,263.20 and 75,100 were taken (low 74,790). Ether last printed about 2,227 dollars (TradingView 2,226.5; Kraken 2,225.04). Prints labeled intraday; crypto's daily candle closes at 00:00 UTC. Bitcoin bullish trigger: a hold through 76,300.70. Bearish trigger: a slip through 74,790.
- Bitcoin about $75,704 against this morning about $75,556; $76,300.70 tagged, $75,263.20 taken
- Ether about $2,227; prints labeled intraday
- Bitcoin bullish trigger: hold $76,300.70; bearish: $74,790
After-Hours and Overnight Watch
US cash still has the closing auction as of 20:00 UTC, with the cash close at 21:00 UTC. Next week: October CPI at 13:30 UTC on 10 November, previous +0.6 percent month on month and +3.7 percent year on year. PPI follows on 13 November at 13:30 UTC. Docket: the calendar and the week ahead. Scenarios to watch: a closing auction that holds the Nasdaq rebound after the hot wage print, or a further oil fade if 89.07 gives way overnight. None of this is a recommendation.
- Cash still open until 21:00 UTC
- Tuesday 10 November, 13:30 UTC: October CPI
- PPI on 13 November at 13:30 UTC
For live prices see the ThriveInMarkets homepage. None of the above is a recommendation. Index prints are intraday as of 20:00 UTC Friday, November 6, 2026.