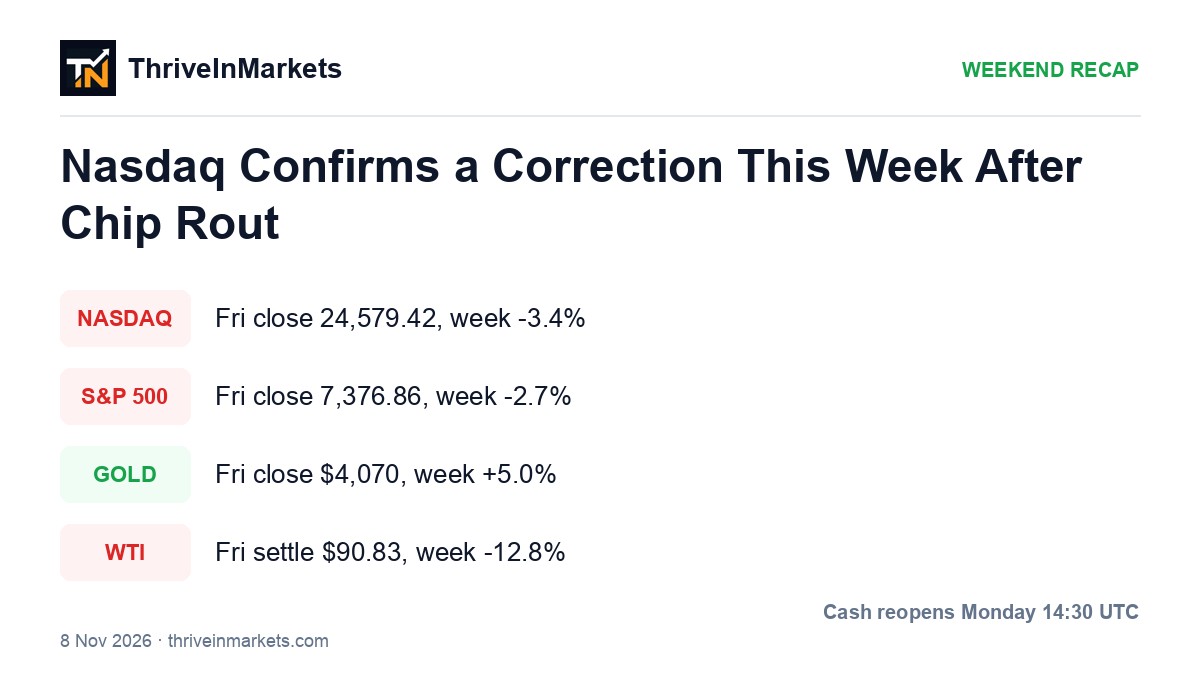
The Nasdaq confirms a correction this week after Thursday's chip rout, and cash equities, gold and oil stay shut until Monday. Friday's cash close left the Nasdaq at 24,579.42, down 3.4 percent on the week. The S&P 500 closed 7,376.86, down 2.7 percent on the week, the worst week since April 2025 (Morningstar). The week in markets ran from November 2 to November 8, 2026. Equity, gold and oil figures below are Friday closes (November 6). Bitcoin and Ether are live as of Sunday. Saturday: weekly markets roundup.
Weekly Scorecard: Nasdaq Loses 3.4 Percent, Oil Drops 12.8 Percent
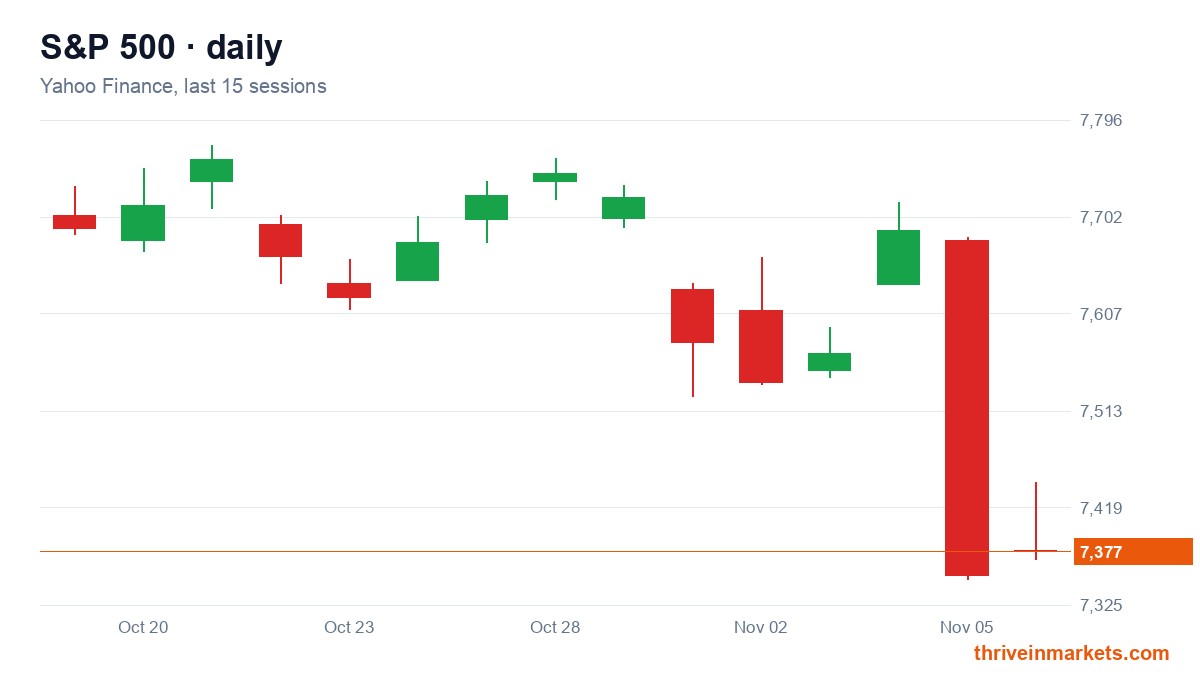
At Friday's cash close the S&P 500 stood at 7,376.86, up 0.31 percent on the day and down 2.7 percent on the week from 7,580.07 (Associated Press, Morningstar). Friday range 7,369.55 to 7,444.20. The week was the largest one-week decline since April 4, 2025, and a fourth straight down week (Dow Jones Market Data). October 6's 7,818.93 record close remains unrepaired. The Nasdaq Composite finished at 24,579.42, down 3.4 percent on the week from 25,437.00. The Dow closed at 51,285.73, down 0.9 percent on the week. West Texas Intermediate's Friday NYMEX settlement was 90.83 dollars, down 12.8 percent from 104.12 (MarketWatch), range 89.07 to 92.53. Spot gold closed Friday about 4,070 dollars (Kitco 4,070.10 at 22:00 UTC; GoldPrice.com 4,070.59), up 5.0 percent from the October 30 one-year low at 3,875.65. Cash reopens Monday at 14:30 UTC.
- S&P 500 -2.7% on the week to a Friday close of 7,376.86; Friday +0.31%, range 7,369.55-7,444.20
- Nasdaq -3.4% at 24,579.42, a fourth down week and a confirmed correction; Dow -0.9% at 51,285.73
- Gold Friday close about $4,070, week +5.0%; WTI settle $90.83, week -12.8%. Cash reopens Monday 14:30 UTC
Biggest Movers of the Week
The Nasdaq Composite closed Thursday at 24,315.00, down 5.52 percent, its deepest one-day drop in 19 months and a 10 percent decline from the October 6 record close (Reuters). The S&P 500 closed 7,353.73, down 4.36 percent, its worst day since April 2025, wiping about 3 trillion dollars of S&P 500 value. The Philadelphia Semiconductor Index dropped about 12 percent. Nvidia fell more than 9 percent. Friday recovered some of the damage, with the Nasdaq up 1.1 percent, but the week still closed red.
Apple reported fiscal-fourth-quarter revenue of 114.5 billion dollars and diluted earnings of 2.10 dollars a share (Apple, MacRumors). The holiday-quarter gross-margin guide of 45 to 46 percent sat under the September print as memory costs climbed. AMD reported third-quarter revenue of 13.4 billion dollars, with Data Center sales a record 8.5 billion dollars, up 97 percent (AMD). Marvell agreed on Monday to buy Lumentum in an all-stock deal with an implied enterprise value of 115 billion dollars; Marvell fell about 13 percent and Lumentum about 19 percent on the announcement (Marvell, Reuters).
- Thursday: Nasdaq -5.52 percent to 24,315.00; S&P 500 -4.36 percent to 7,353.73; about 3 trillion dollars of S&P 500 value wiped
- Apple revenue 114.5 billion dollars with a 45-46 percent holiday-margin guide; AMD Data Center 8.5 billion (+97 percent)
- Marvell to buy Lumentum for 115 billion dollars enterprise value; Friday's chip bounce did not repair the week
Macro: Payrolls Beat, Gold Reclaims 4,000, Oil Loses the War Premium
The Bureau of Labor Statistics printed October payrolls at +165,000 at 13:30 UTC Friday, against a FactSet median of +65,000. Unemployment fell to 4.1 percent. Average hourly earnings rose 0.4 percent on the month and 3.1 percent on the year. August and September were revised up a combined 84,000 (BLS). CME FedWatch sat near 77 to 78 percent for a December quarter-point increase (CNBC 76.8 percent).
Democrats took the Senate and the House on Tuesday, and markets priced tighter scrutiny of data-center buildout (Reuters). The Reserve Bank of Australia raised the cash rate 25 basis points to 4.85 percent at 03:30 UTC Tuesday, a 6-3 vote (RBA). The Bank of England raised Bank Rate 25 basis points to 4.00 percent on Thursday, the first increase since 2023, and sees inflation near 5 percent by mid-2027 (Bank of England). West Texas Intermediate last settled 90.83 dollars, down 12.8 percent on the week from 104.12, as Iran-talk hopes took the war premium out on Monday (Monday's evening review). Spot gold closed Friday about 4,070 dollars, up 5.0 percent from the October 30 one-year low, after reclaiming 4,000 on the midterm sweep. Gold bullish trigger: a reclaim of Kitco's Friday high at 4,107.90. Bearish trigger: a slip through 4,029.50, then 4,000. Oil bullish trigger: a hold of Friday's high at 92.53. Bearish trigger: a slip through 89.07.
- Payrolls +165,000 against +65,000 seen; wages +0.4 percent; December hike odds about 77 to 78 percent
- RBA hiked to 4.85 percent; Bank of England hiked to 4.00 percent, first increase since 2023
- WTI Friday settle $90.83, week -12.8%; gold Friday close about $4,070, week +5.0%
Crypto: Bitcoin Holds $75,823 After a 1.28 Billion ETF Outflow Week
Binance began restoring withdrawals in phases at 06:00 UTC on Sunday, November 1, three days after the 6.3 billion dollar theft. Between 06:00 and 15:30 UTC the exchange processed 4.649 billion dollars of withdrawals and 1.01 billion of deposits, a net outflow of about 3.64 billion dollars (Binance).
Bitcoin last printed 75,823 dollars live on Sunday (TradingView 75,823 at about 10:12 UTC; CoinMarketCap 75,791). TradingView put the one-week change at -1.95 percent. Price reclaimed 80,000 on Wednesday, then lost that handle in Thursday's equity rout and briefly traded below 75,000 on Friday. US spot Bitcoin ETFs posted about 1.28 billion dollars of net outflows over the seven days through Friday, with BlackRock's IBIT 403 million on Friday (Alpha Finance, The Block / SoSoValue). Ether holds near 2,233.7 dollars live (TradingView), with a one-week change of -0.50 percent. Ether ETFs lost about 365 million dollars on the week. BTC bullish trigger: a reclaim of 80,000 dollars. Bearish trigger: a slip through 75,000.
- Bitcoin ~$75,823 (live); TV 1-week -1.95%; seven-day Bitcoin ETF outflows about $1.28B
- Ether ~$2,234 (live); TV 1-week -0.50%; Ether ETFs about -$365M
- Binance net outflow about $3.64B on Sunday; BTC bullish trigger: reclaim $80,000; bearish: $75,000
The Week Ahead: October CPI, Then Veterans Day and PPI
Cash reopens Monday at 14:30 UTC. These are scenarios for next week, not instructions. Docket: calendar. Guide: the CPI explainer.
- Monday, November 9: China CPI and PPI at 01:30 UTC. Fed's Bowman, Goolsbee and Barkin from 13:40 UTC. Bank of England Governor Bailey speaks at 17:25 UTC.
- Tuesday, November 10, 13:30 UTC: October CPI, seen +0.3 percent headline and +0.2 percent core after September's +0.6 / +0.3. Last CPI before the December 8-9 FOMC. Fed's Waller speaks at 09:00 UTC.
- Wednesday, November 11: Veterans Day. US cash equities are open; the Treasury market is shut. German CPI final at 07:00 UTC. OPEC Monthly Oil Market Report around 10:00 UTC. EIA inventories move to Thursday 17:00 UTC.
- Thursday, November 12, 07:00 UTC: UK Q3 GDP. US claims at 13:30 UTC, existing home sales at 15:00 UTC, delayed EIA at 17:00 UTC. Cisco and Applied Materials report at 21:00 UTC.
- Friday, November 13, 13:30 UTC: October PPI, seen +0.4 percent headline and +0.3 percent core. Eurozone GDP second estimate at 10:00 UTC. Nvidia reports Monday, November 17.
Traders watching 7,376.86 as the cash reference. Bullish trigger: a reclaim of Friday's 7,444.20 then Thursday's 7,681.29. Bearish trigger: a slide through Friday's 7,369.55 low, then Thursday's 7,350.35.
- Tuesday 13:30 UTC: October CPI, the last print before the December FOMC, seen +0.3 / +0.2 after +0.6 / +0.3
- Wednesday: Veterans Day, bonds shut; EIA delayed to Thursday 17:00 UTC. Thursday: UK GDP at 07:00 UTC; Cisco and Applied after the close
- S&P bullish trigger: reclaim 7,444.20 then 7,681.29; bearish: 7,369.55 then 7,350.35. Cash reopens Monday 14:30 UTC
ThriveInMarkets publishes market commentary for general information only and does not provide personal investment advice. Equity, gold and WTI figures are Friday closes for November 6, 2026. Equities reopen Monday. Bitcoin and Ether are live as of 10:12 UTC on November 8, 2026. Levels cited are observations, not instructions to buy or sell any asset. ThriveInMarkets is based in Cyprus and is not a licensed investment adviser.