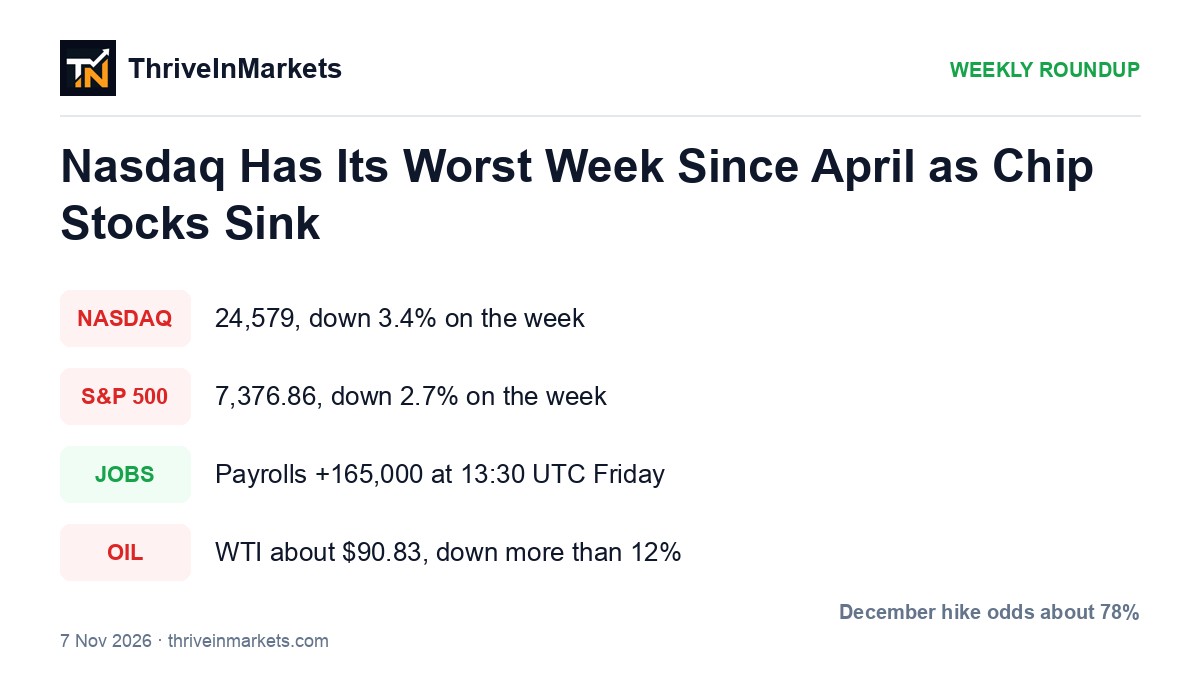
The Nasdaq had its worst week since April as chip stocks sank. The week in markets ran from November 1 to November 7, 2026. Thursday's AI selloff took the S&P 500 down 4.36 percent, confirmed a Nasdaq correction, and wiped about 3 trillion dollars of S&P 500 value. Friday's bounce after a 165,000 payrolls beat did not repair the week: the Nasdaq closed 24,579.42, down 3.4 percent, its fourth straight weekly decline (Reuters via Moneycontrol, Wall Street Journal). The S&P 500 closed 7,376.86, down 2.7 percent, its worst week since April 2025. Catch up on Friday's morning analysis and last week's roundup.
Top Stock Stories of the Week
Thursday's AI rout confirms a Nasdaq correction
The Nasdaq Composite closed Thursday at 24,315.00, down 5.52 percent, its deepest one-day drop in 19 months and a 10 percent decline from the October 6 record close (Reuters). The S&P 500 closed 7,353.73, down 4.36 percent, its worst day since April 2025. The Dow fell 3.44 percent to 51,523.06. The Philadelphia Semiconductor Index dropped 12.25 percent. Japan's Nikkei 225 then closed Friday at 57,434.77, down 5.96 percent, and South Korea's Kospi tripped circuit breakers for 20 minutes (Friday morning).
Why it matters: the catalyst was political. Democrats took the Senate and the House on Tuesday, with about 54 Senate seats and more than 250 House seats, and flipped the Texas governor's mansion. Goldman Sachs said states where Democrats are likely to restrict data centers account for about 45 percent of planned US capacity, Texas alone about 25 percent. Friday recovered some of the damage, with the semiconductor index up 4.2 percent, AMD about 11 percent and Nvidia 2.8 percent, but the week still closed red.
Apple beats, then the holiday-margin guide does the work
Apple reported fiscal-fourth-quarter revenue of 114.5 billion dollars, up 12 percent, and diluted earnings of 2.10 dollars a share (Apple, MacRumors). iPhone sales were a September-quarter record and Services hit an all-time high. The stock still faded. The holiday-quarter gross-margin guide of 45 to 46 percent sat under about 46.3 percent seen, as memory costs climbed (TrendForce, Tuesday's morning analysis). Cash closed Monday at 338.32 dollars, down 1.83 percent, then slipped further Tuesday. Why it matters: Apple was the last Magnificent 7 print before Nvidia on November 17, and the guide told investors that the AI-memory squeeze is now an iPhone-margin story.
AMD doubles data-center sales; Qualcomm's handset engine rolls off
AMD reported third-quarter revenue of 13.4 billion dollars, up 45 percent (AMD 8-K). Data Center sales were a record 8.5 billion dollars, up 97 percent, now about 64 percent of the company. Fourth-quarter revenue was guided to about 17 billion dollars, plus or minus 3 percent. After hours the stock tagged about 529.94 dollars then faded as the midterm sweep priced, as Wednesday's morning analysis laid out. Friday's cash bounce of about 11 percent still left the name inside Thursday's drawdown. Qualcomm's fiscal-fourth-quarter revenue was 10.32 billion dollars, down 8 percent, as handset sales fell 26 percent on Apple's shift to its own modems; the offset was a multi-generational AI data-center collaboration with Amazon (Qualcomm 8-K). Why it matters: AMD's beat was real and the guide is faster, and the market still treated both names as data-center-policy stocks once Texas and Congress flipped.
- Nasdaq closed 24,579.42, down 3.4 percent on the week; S&P 500 7,376.86, down 2.7 percent, the worst week since April 2025
- Thursday: S&P 500 -4.36 percent to 7,353.73; Nasdaq -5.52 percent; about 3 trillion dollars of S&P 500 value wiped
- Apple revenue 114.5 billion dollars with a 45-46 percent holiday-margin guide; AMD Data Center 8.5 billion (+97 percent) and Q4 about 17 billion
Top Crypto Stories of the Week
Binance reopens and 3.64 billion dollars leaves in the first hours
Binance began restoring withdrawals in phases at 06:00 UTC on Sunday, November 1, three days after the 6.3 billion dollar theft. By 12:36 UTC all 15 networks in the first phase were open. Between 06:00 and 15:30 UTC the exchange processed 4.649 billion dollars of withdrawals and 1.01 billion of deposits, a net outflow of about 3.64 billion dollars, or 2.1 percent of the 171 billion dollars of assets in the October 28 proof of reserves (Binance). Replenishment of stolen assets rose from about 95 percent on Sunday to about 98 percent by Wednesday. The weekend Bitcoin levels note had framed Sunday as the test. Why it matters: the reopen was orderly enough that bitcoin did not gap lower on Sunday, and the 2.1 percent outflow says most balances stayed put.
Bitcoin ETFs leak 1.28 billion dollars as price loses 80,000 then 75,000
Bitcoin last printed about 75,900 dollars on Saturday, down from about 77,300 a week earlier. It reclaimed 80,000 on Wednesday as the midterm result priced, then lost that handle in Thursday's equity rout and briefly traded below 75,000 on Friday, the lowest since mid-September (BitGo, CoinMarketCap). US spot Bitcoin ETFs posted about 1.28 billion dollars of net outflows over the seven days through Friday, with BlackRock's IBIT alone 403 million on Friday (Alpha Finance). Ether last printed about 2,244 dollars. Ether ETFs lost about 365 million dollars on the week. Why it matters: Wednesday's 80,000 dollar reclaim arrived with only a thin ETF bid. Price ran ahead of the product, then gave it back with equities.
Solana leads the large-cap lag; XRP funds sit still
Solana last printed about 90 dollars, down about 6 percent from last Saturday's about 96 dollars, the weakest large-cap on the week (CoinGecko). US spot Solana ETFs lost about 25 million dollars over seven days. XRP last printed about 1.17 dollars, down about 6 percent, and XRP ETFs recorded zero net flow for a third straight session into Thursday even as they remain the 30-day inflow exception at about 15.4 million dollars (Alpha Finance). Ripple minted about 110.57 million dollars of RLUSD on November 2 as Binance restored XRP withdrawals. Why it matters: the top-50 market is not moving as one. Solana is still paying for October ETF outflows and for tokens that left Binance in the hack. XRP is the regulated-product exception that stopped adding dollars this week.
- Binance net outflow about 3.64 billion dollars on Sunday; replenishment about 98 percent by Wednesday
- Bitcoin last near 75,900 dollars; seven-day Bitcoin ETF outflows about 1.28 billion
- Solana about 90 dollars (week about -6 percent); XRP ETFs zero net flow into Thursday
M&A, Partnerships, Deals
Marvell agreed on Monday to buy Lumentum in an all-stock deal with an implied enterprise value of 115 billion dollars, 4.500 Marvell shares per Lumentum share, a 23.9 percent premium to the October 28 close (Marvell, Reuters). Marvell holders would own about 67 percent of the combined company. Closing is aimed at the first half of 2028. Marvell fell about 13 percent and Lumentum about 19 percent on the announcement. AMD separately said it had agreed to acquire World Labs and Taalas. Qualcomm announced a multi-generational AI data-center collaboration with Amazon. Why it matters: the week's largest deal is an optical-networking bet on the same AI buildout that equity investors spent Thursday selling. The close is 2028, so investors can fade the stocks without killing the strategic read.
- Marvell to buy Lumentum for 115 billion dollars enterprise value, close aimed at first-half 2028
- AMD agreed to acquire World Labs and Taalas; Qualcomm tied a data-center collab to Amazon
- Qualcomm's Amazon collab is the partnership overlay on a 115 billion dollar optical deal
Regulatory & Macro
The Bureau of Labor Statistics printed October payrolls at +165,000 at 13:30 UTC Friday, against a FactSet median of +65,000, after September's first print of +29,000. Unemployment fell to 4.1 percent. Average hourly earnings rose 0.4 percent on the month and 3.1 percent on the year. August and September were revised up a combined 84,000 (BLS). CME FedWatch, via LSEG, sat near 78 percent for a December quarter-point increase, against about 68 percent in Friday's morning note. Guide: the jobs-report explainer.
The Reserve Bank of Australia raised the cash rate 25 basis points to 4.85 percent at 03:30 UTC Tuesday, a 6-3 vote and the highest cash rate since 2008 (RBA). The Bank of England raised Bank Rate 25 basis points to 4.00 percent on Thursday, 8-1, the first increase since 2023. Catherine Mann dissented for 50 basis points. The Monetary Policy Report sees inflation near 5 percent by mid-2027 (Bank of England). West Texas Intermediate last settled about 90.83 dollars, down more than 12 percent on the week from Friday October 30's 104.12 settle, as Iran-talk hopes took the war premium out on Monday (Monday's evening review). Spot gold last printed about 4,072 dollars, up about 5 percent from the October 30 one-year low at 3,875.65. Why it matters: three English-speaking central banks have now hiked or held-hawkish into the same oil shock, Friday's payrolls beat keeps December live for the Fed, and oil's 12 percent weekly drop is the one input that could still fade that hike if it sticks into Tuesday's CPI.
- Payrolls +165,000 against +65,000 seen; wages +0.4 percent; December hike odds about 78 percent
- RBA hiked to 4.85 percent; Bank of England hiked to 4.00 percent, 8-1, first increase since 2023
- WTI about 90.83 dollars, week down more than 12 percent; gold about 4,072 dollars, week about +5 percent
Week Ahead: What to Watch
- Tuesday, November 10, 13:30 UTC: October CPI, seen +0.3 percent headline and +0.2 percent core after September's +0.6 / +0.3. This is the last CPI before the December 8-9 FOMC. Guide: the CPI explainer.
- Wednesday, November 11: Veterans Day. US cash equities are open; the Treasury market is shut. EIA inventories move to Thursday 17:00 UTC.
- Thursday, November 12, 07:00 UTC: UK Q3 GDP after the Bank of England's 8-1 hike. Cisco and Applied Materials report after the US close at 21:00 UTC.
- Friday, November 13, 13:30 UTC: October PPI, seen +0.4 percent headline and +0.3 percent core. Nvidia reports Monday, November 17.
The docket is on the ThriveInMarkets calendar. The question the week leaves hanging is whether Thursday's AI session is the template into Nvidia, or whether Friday's chip bounce plus a cooler CPI can put the correction behind the Nasdaq.
- Tuesday 13:30 UTC: October CPI, the last print before the December FOMC
- Wednesday: Veterans Day, bonds shut; EIA delayed to Thursday 17:00 UTC
- Thursday: UK GDP at 07:00 UTC; Cisco and Applied after the close; Friday PPI at 13:30 UTC