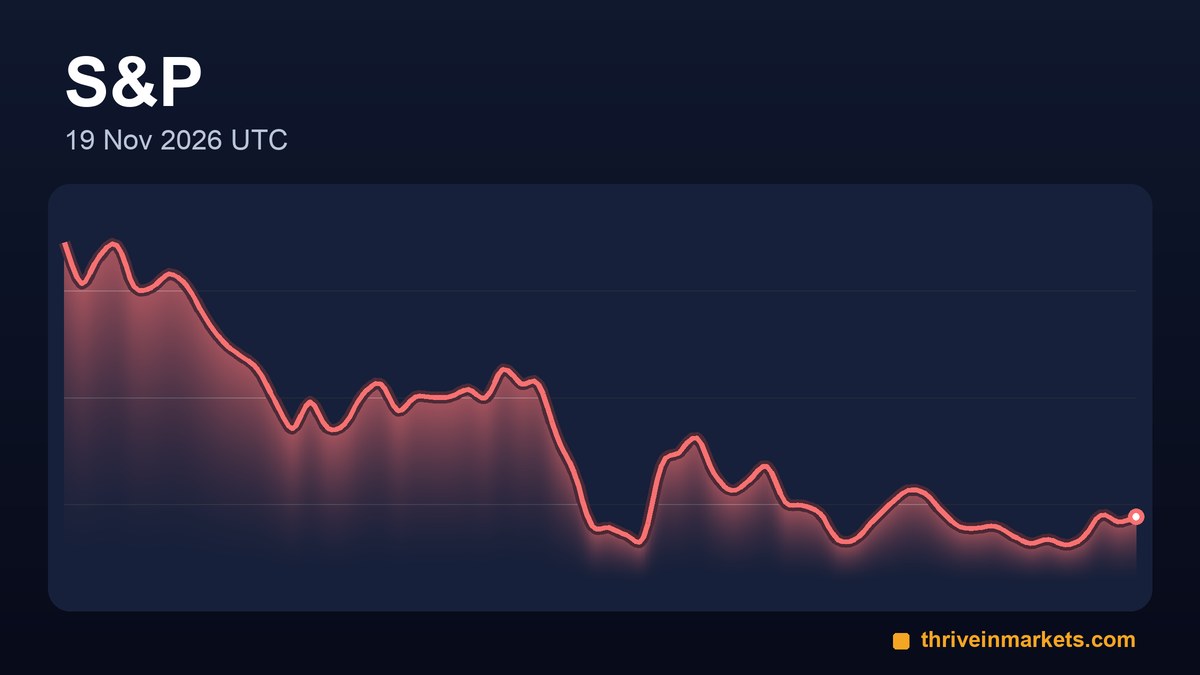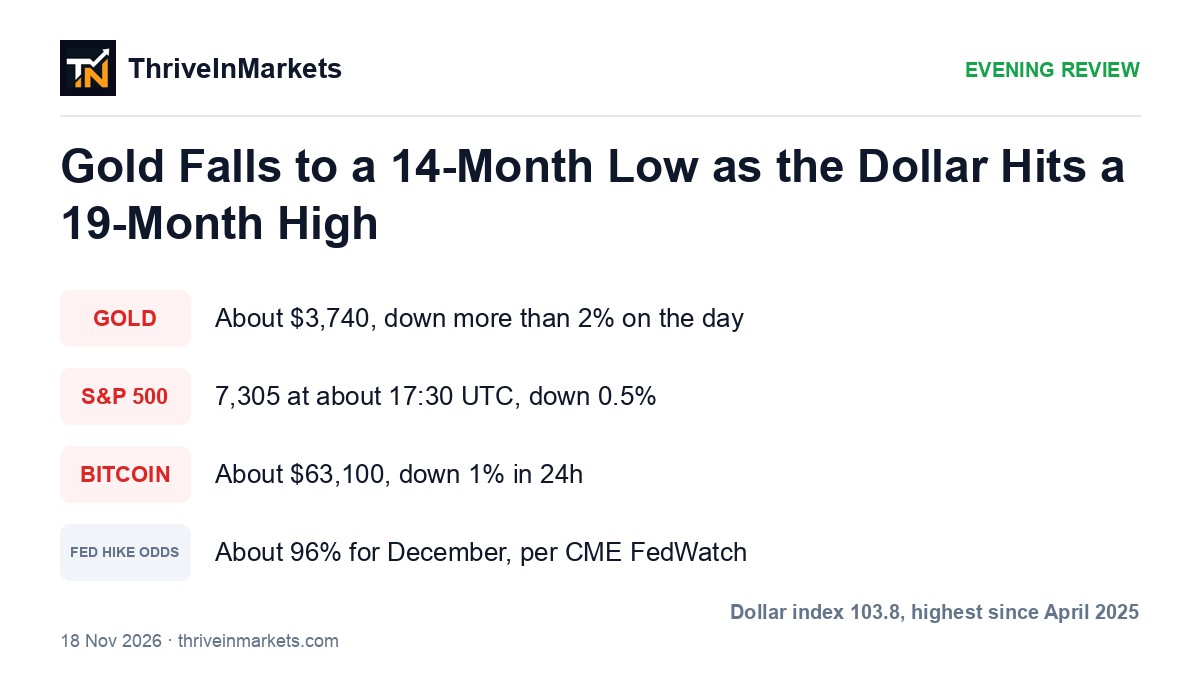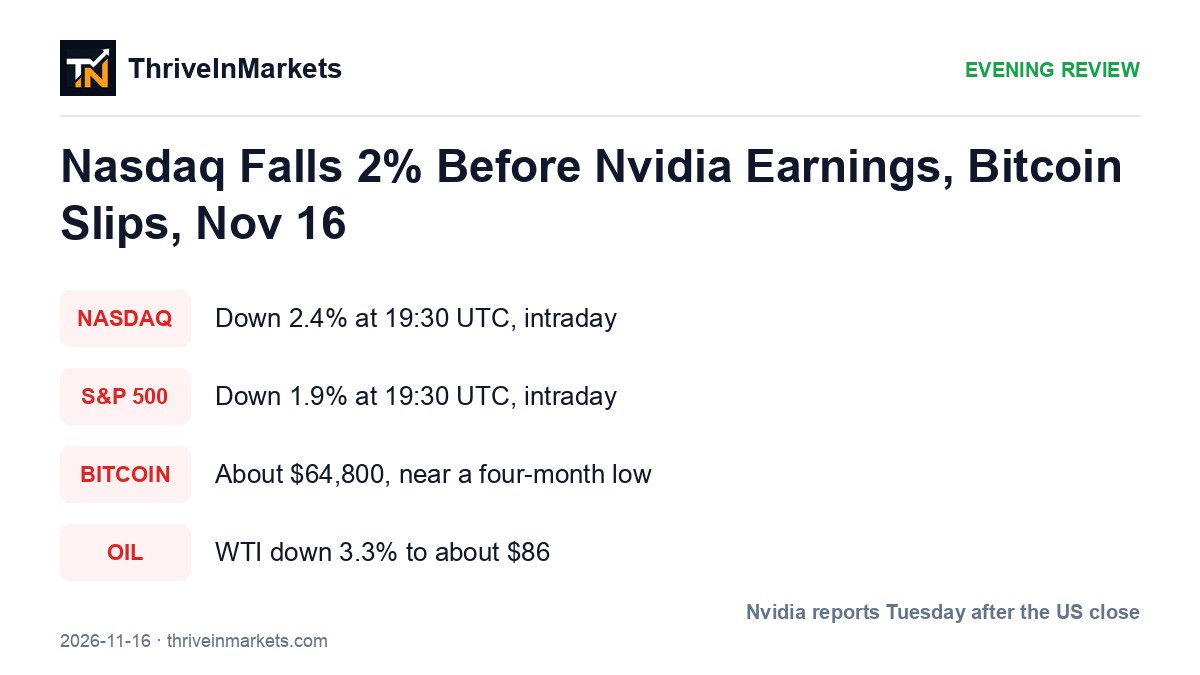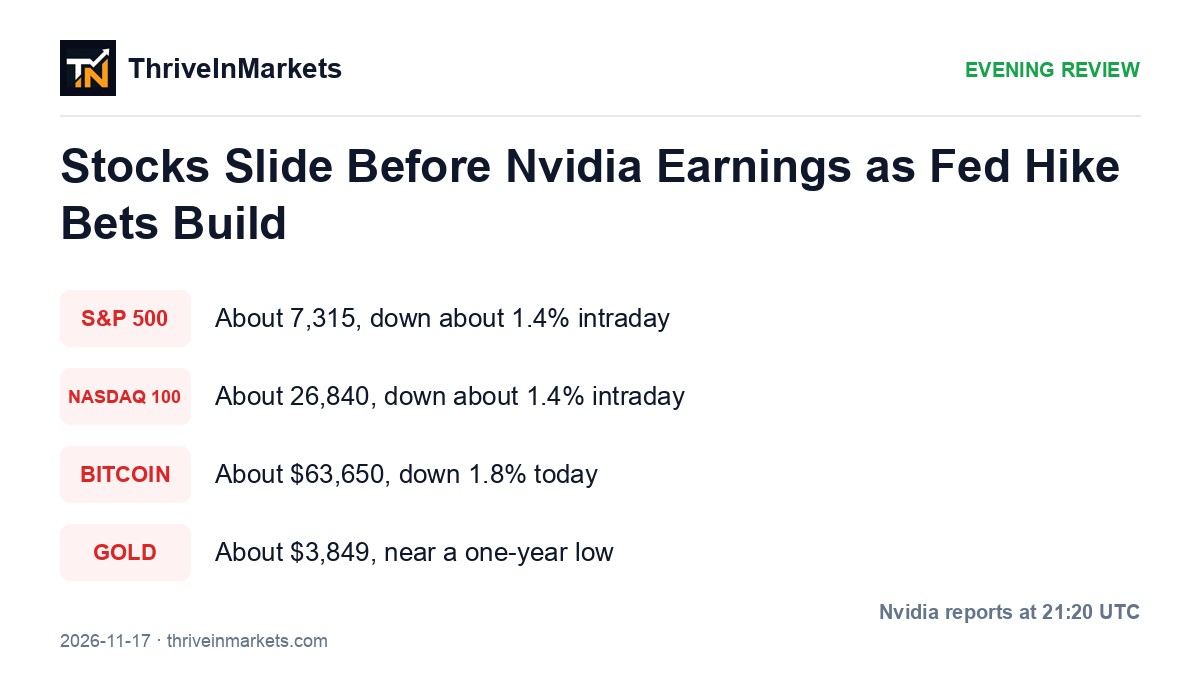
The S&P 500 fell about 1.4% on Tuesday as hawkish Fed comments and rising Treasury yields weighed on stocks before Nvidia reports earnings. As flagged in this morning's analysis, futures had only edged higher, and the session turned lower once retail sales and Fed speakers arrived.
Prices as of 19:45 UTC. US cash markets are still open, so stock moves are intraday and crypto is mid-day.
- Stocks fell because the Fed looks set to keep raising rates, and long Treasury yields near 5.1% make expensive tech harder to justify.
- Software was hit hardest, with Salesforce down about 9% as investors worry about AI competition.
- Nvidia reports at 21:20 UTC, and its guidance could decide whether the AI selloff continues.
The Close: Dow Leads Losses
The Dow fell about 1.8% and the S&P 500 lost about 1.4%, around 7,315. The Nasdaq 100 was down a similar amount near 26,840. These are intraday levels, not closing prints, and different data providers showed slightly different moves.
US retail sales rose 0.2% in October, a touch above forecasts, and the gain was stronger once autos and fuel were stripped out. Industrial production fell 0.4% and import prices jumped 1.1%, which fed worries that inflation is not cooling.
Scenarios to watch: a hold above the 7,300 area would show buyers stepping in, while a close below it would deepen the pullback.
- Solid spending data keeps the rate-hike story alive.
- Selling was broad, with small caps also down about 1.4%.
Story of the Day: Fed Hike Bets and Software Rout
St. Louis Fed President Alberto Musalem said the Fed may need several more rate increases before spring 2027, and markets now price roughly a 95% chance of a hike in December. The 10-year Treasury yield sits near 5.13%, close to its highest level in a month.
Software stocks took the brunt. Salesforce fell about 9%, Intuit about 7% and Adobe about 4%, ahead of Anthropic's IPO, which keeps its proposed range of $70 to $78 a share. Disney rose after raising its dividend, while Home Depot slipped about 2% even after beating forecasts and naming a new CEO.
Scenarios to watch: if Nvidia's guidance steadies chip stocks, the pullback could pause, while a weak outlook would add pressure on the AI trade.
- Higher-for-longer rates are the main pressure on growth stocks.
- Software is trading as the weak link in the AI story.
Crypto Check: Bitcoin Drifts Lower
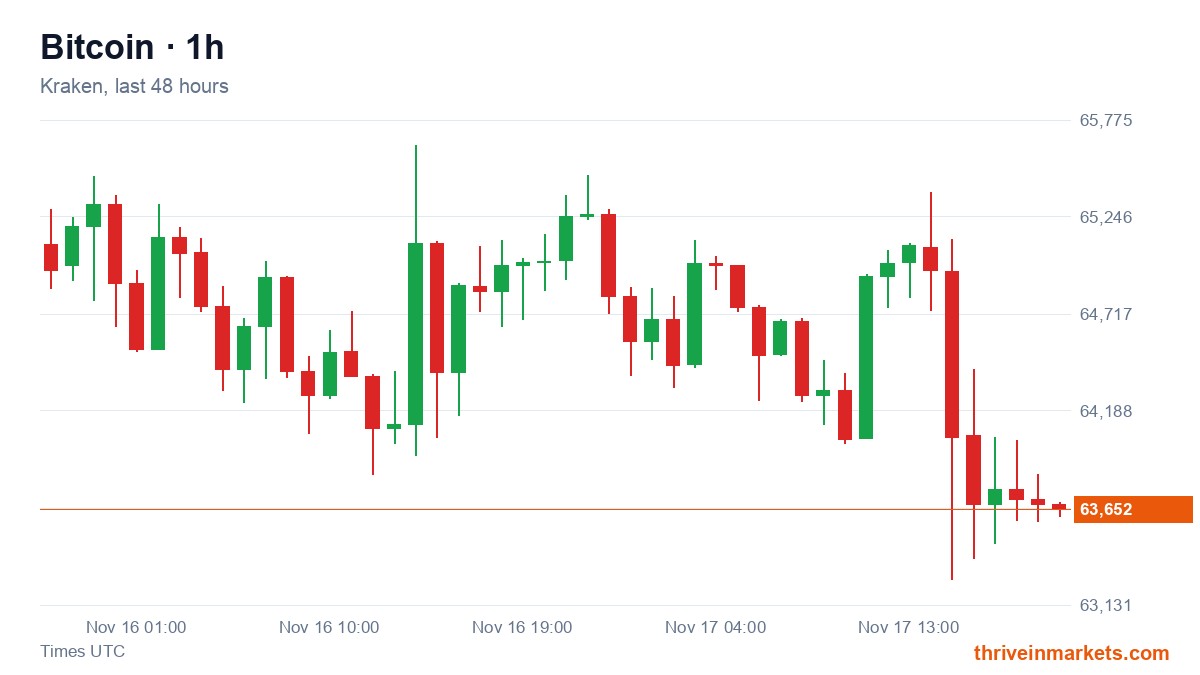
Bitcoin is near $63,650, down about 1.8% on the day, and Ether is around $1,790. Crypto has tracked tech stocks lower this week, with spot Bitcoin ETF outflows still a headwind. Crypto's daily candle closes at 00:00 UTC, so these are intraday levels.
Scenarios to watch: a reclaim of $65,000 would suggest selling is easing, while a break below $62,000, the weekend low, would expose $60,000.
- Bitcoin is moving with Nasdaq, so Nvidia matters here too.
- The weekend low near $62,000 is the level traders are watching.
Oil and Gold: Supply Glut and Strong Yields
WTI crude is trading near $84, lower again as Middle East exports recover and the supply surplus view grows. Gold is near $3,849, close to its lowest level in more than a year, because high yields reduce the appeal of a metal that pays no interest.
- Oil is driven by supply forecasts more than by tanker risk.
- Gold stays under pressure while the 10-year yield holds above 5%.
After-Hours and Overnight Watch
All times in UTC:
- 21:20 UTC: Nvidia earnings, its first report since CEO Jensen Huang announced his resignation on 12 November. Huang said he would be honored to return if the board wished.
- Overnight: Asian markets react to Nvidia and the US chip export curbs.
- Wednesday: FOMC meeting minutes, which may show how deeply officials discussed more rate hikes.
Anthropic's market debut is also due later this week, a key test of appetite for AI companies.
- Nvidia's guidance is the main event after the bell.
- FOMC minutes on Wednesday test the rate-hike narrative.
This is market commentary for information only, not investment advice. ThriveInMarkets is based in Cyprus.