Oil slipped on Tuesday as banks and the International Energy Agency pointed to a growing supply surplus, while new US limits on advanced AI chip exports hit Asian stocks. S&P 500 futures edged higher after a third straight daily loss, with Nvidia earnings due after the US close.
Prices as of 06:30 UTC.
- Oil is falling because the IEA sees supply running ahead of demand, even with tanker attacks near Hormuz.
- Asian chip and AI stocks sold off after Washington tightened export licensing for advanced chips and servers.
- Gold is hovering near a one-year low while 10-year Treasury yields stay above 5%.
Oil: Supply Glut Outweighs Hormuz Risk
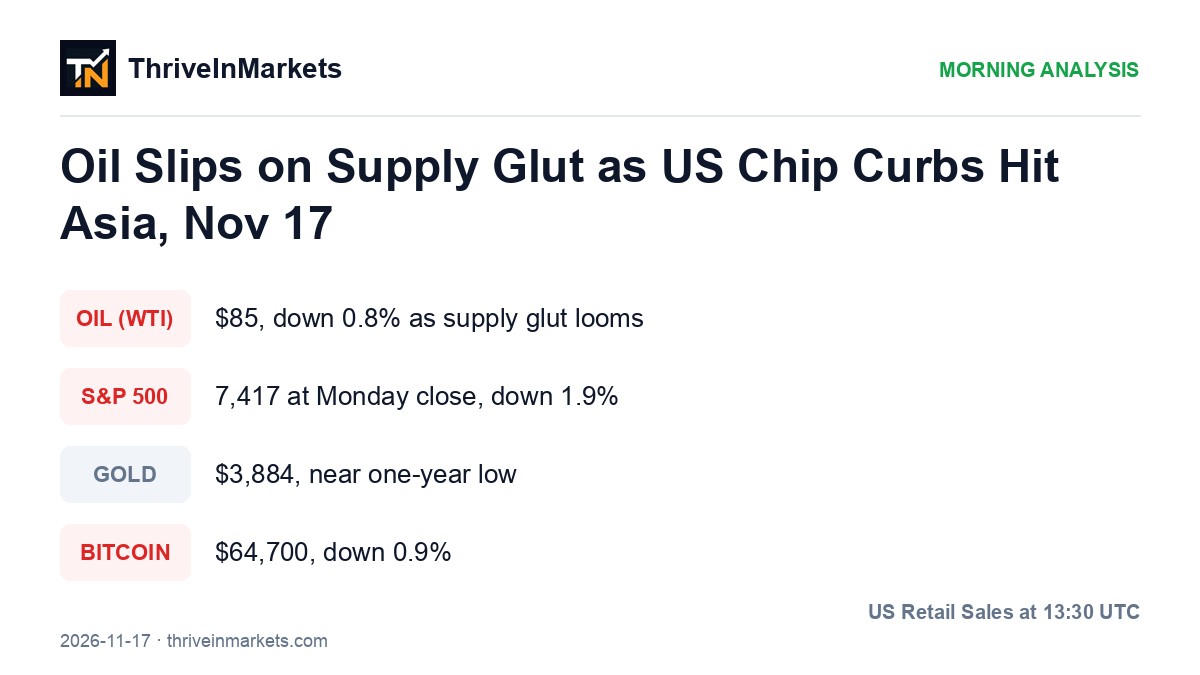
WTI crude is trading near $85, down about 0.8% on the day, with Brent below $92. The IEA expects global supply to exceed demand by about 1.7 million barrels a day this quarter, and Middle East exports are recovering faster than expected.
Attacks on tankers near the Strait of Hormuz keep a floor of risk under prices, and OPEC+ meets on 29 November to set 2027 output policy.
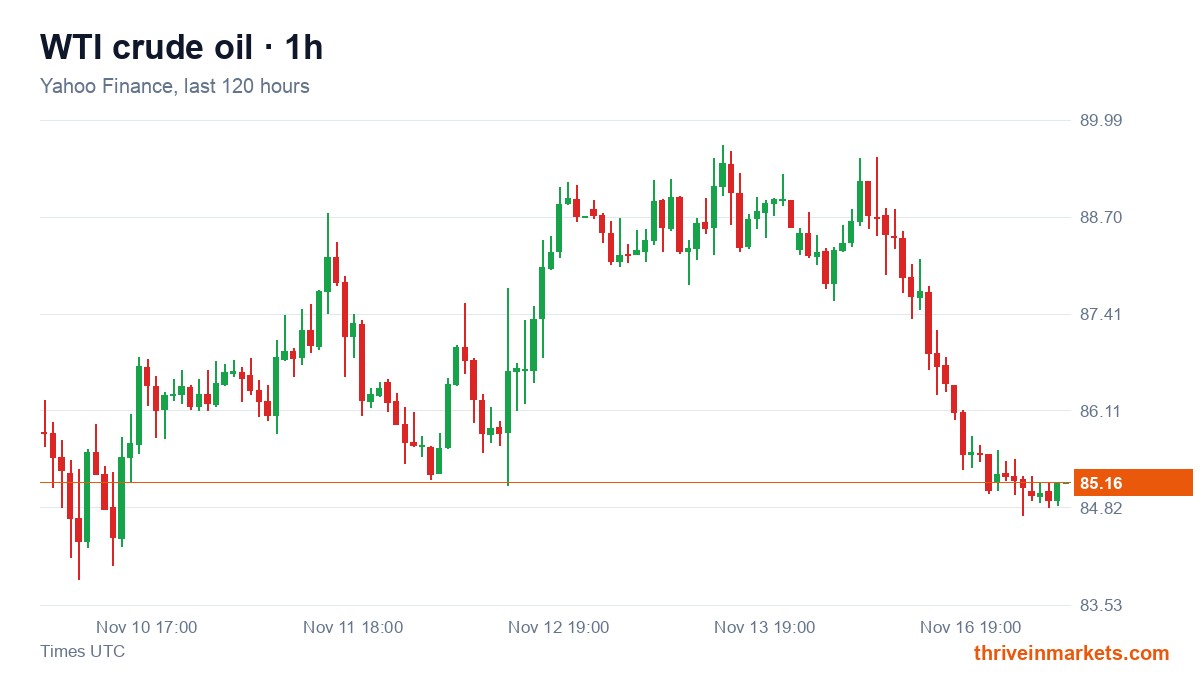
Scenarios to watch: a hold above $85 would suggest the slide is pausing, while a move toward $80 would extend the supply-glut narrative.
- The supply forecast is driving prices more than geopolitics for now.
- OPEC+ on 29 November is the next big policy event.
Stocks: Chip Curbs Add to Nvidia Nerves
Japan's Topix fell about 1.4% and Hong Kong's Hang Seng lost roughly 1%. Taiwan and South Korea led the regional losses as the new US licensing rules weighed on AI-linked names. China's CSI 300 touched its lowest level since July 2025 before paring losses.
On Wall Street, the S&P 500 closed Monday at 7,417, down 1.9%, and the Nasdaq Composite lost 2.5%. Nvidia fell 4.1% in its worst week since April 2025 and reports after the close at 21:20 UTC. CNN also lists the market debut of Anthropic among this week's events.
Scenarios to watch: a recovery above 7,500 would show dip buyers returning, while another close below Monday's level would deepen the pullback before the Nvidia report.
- Futures are slightly higher, but three straight daily losses leave sentiment fragile.
- Nvidia's guidance could move the whole AI trade.
Gold: Steady Near a One-Year Low
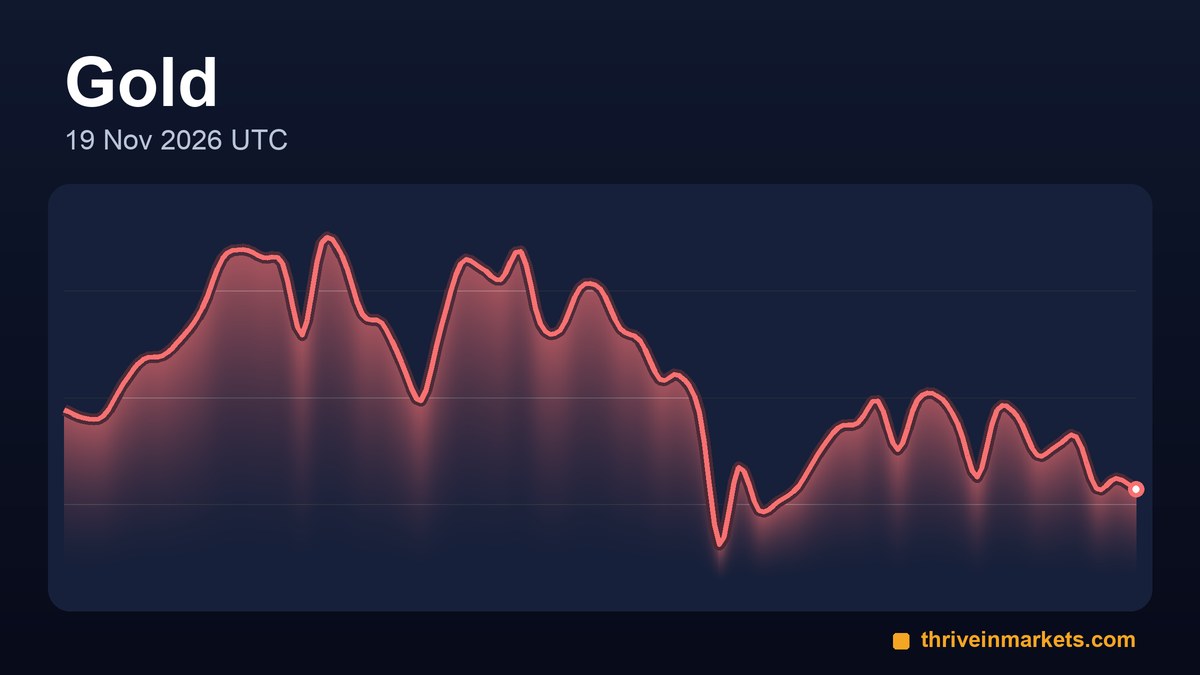
Gold is near $3,884, little changed after touching a one-year low close to $3,830 on Monday. The 10-year Treasury yield is around 5.12% and the dollar index is slightly softer.
A metal that pays no interest struggles when yields are this high and markets price a possible December Fed hike. Today's US retail sales could shift that pricing.
Scenarios to watch: a hold above $3,830 keeps the low intact, while a break below it would weaken the structure.
- Yields, not fear, are the main driver.
- Strong retail sales would likely pressure gold again.
Crypto: Bitcoin Holds Above $64,000
Bitcoin is near $64,700, down about 0.9% in a day, after sliding to about $62,000 over the weekend. Ether is around $1,830. US spot Bitcoin ETFs saw roughly $1.9 billion of outflows over the seven sessions to 13 November, and thin liquidity has amplified forced selling.
Scenarios to watch: a close above $65,600 would suggest the selling is easing, while a break below $62,000 would expose the $60,000 area.
- ETF outflows are the main headwind.
- Bitcoin trades with tech stocks, so Nvidia matters.
What's Next: Retail Sales and Nvidia
The day's calendar, all in UTC:
- 07:00 UTC: UK labour market report
- 10:00 UTC: German and Eurozone ZEW sentiment
- 13:30 UTC: US retail sales for October; September rose 0.8%
- 14:15 UTC: US industrial production
- 21:20 UTC: Nvidia earnings after the close
Earlier, the RBA minutes at 00:30 UTC leaned hawkish. Another strong retail sales print would harden December hike pricing, while a clear slowdown would ease it. For the longer view, see yesterday's analysis.
- Retail sales at 13:30 UTC tests the rate-hike story.
- Nvidia at 21:20 UTC tests the AI trade.
This is market commentary for information only, not investment advice. ThriveInMarkets is based in Cyprus.