Bookmark this one. Last week was Chair Kevin Warsh's first hike and a Bank of Japan move to 1.25 percent. This week is the calendar: Thursday's Trump-Xi summit, Wednesday's flash PMIs, and Costco after the close. Japan is shut Monday through Wednesday. The S&P 500 closed Friday at 7,650.50; E-mini December futures are near 7,745. Bitcoin is near 81,440 dollars. Catch up on last week here: weekly markets roundup.
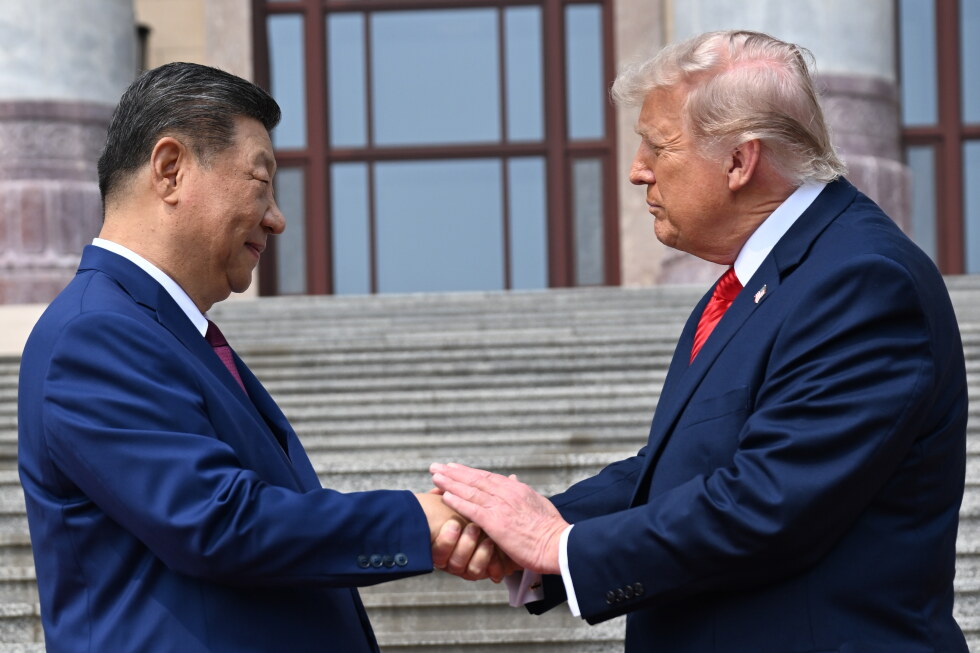
The Big One: Trump Hosts Xi Thursday
The week pivots on Thursday, September 24. President Xi Jinping arrives at Joint Base Andrews on Wednesday for his first White House visit in a decade, then sits with President Trump on Thursday for talks and a state dinner (Associated Press, Reuters). The market question is whether the two extend the tariff truce that expires November 10. White House officials have played down breakthroughs. Scott Bessent and He Lifeng held prep talks in New York on Sunday.
Rare earths, Taiwan, and Iran sit in the background. A contained readout that extends the truce would bid the chip complex. A rare-earth or Taiwan headline would reprice the same names first. October Fed follow-up odds sat about 55 to 58 percent after Warsh's unanimous hike to 3.75-4.00 percent. Docket: calendar.
- Thursday: Xi's first White House visit in a decade; talks and a state dinner
- The live question is an extension of the tariff truce that expires November 10
- Rare earths, Taiwan, and Iran are the headline risks around the readout
- October hike odds about 55-58% into a Fed-speaker week off blackout
Economic Calendar, Day by Day
Consensus versus prior. Tokyo cash is shut Monday through Wednesday for Silver Week and reopens Thursday into the summit. Last Friday was quarterly quad-witching; this Friday is weekly options expiry, not monthly OpEx. The Nasdaq-100 rebalance takes effect Monday, SpaceX's weight rising to about 2.82 percent.
- Monday, Sep 21: Japan shut. China loan prime rates seen unchanged at 3.00 and 3.50 percent. Chicago Fed 12:30 UTC, about 0.2 after -0.08. Goolsbee, Lagarde, and Macklem speak. US cash opens 13:30 UTC.
- Tuesday, Sep 22: Japan still shut. UK public-sector borrowing 06:00 UTC, about -15.7 billion after -1.8 billion. Richmond Fed 14:00 UTC, about 5 after 4. Williams speaks.
- Wednesday, Sep 23: Flash PMIs are the data pillar. Euro area about 08:00 UTC (manufacturing 52.6 after 52.7; services 51.4 after 51.6). UK 08:30 UTC (manufacturing 51.4 after 51.7; services 52.0 after 52.5). US flash 13:45 UTC: manufacturing 53.5 after 53.9, services 55.9 after 56.5 (WSJ). August composite was 56.0. EIA crude 14:30 UTC. Xi lands at Andrews.
- Thursday, Sep 24: Tokyo reopens. Australia jobs 01:30 UTC, +20,900 after -15,800. SNB 07:30 UTC, hold at 0.00 percent. Norges Bank (4.25 percent) and the Riksbank (hold at 1.75 percent) decide the same morning. Claims 12:30 UTC, 204,000 after 196,000. New home sales 14:00 UTC, 620,000 after 607,000. Trump-Xi at the White House.
- Friday, Sep 25: Bailey speaks about 09:15 UTC. Durable goods 12:30 UTC, -0.3 percent after +1.1 percent; core capital goods is the capex read. Michigan final 14:00 UTC, 47.1 after 47.8. Weekly OpEx. Deribit quarterly bitcoin and ether options expire.
- Mon-Wed: Japan Silver Week; China LPR Monday; Richmond Fed Tuesday; flash PMIs Wednesday 13:45 UTC
- Thursday: SNB hold at 0.00%; Norges Bank and Riksbank; claims 204,000 after 196,000; new home sales 620,000
- Friday: durable goods -0.3% after +1.1%; Michigan 47.1 after 47.8; weekly OpEx, not monthly
- US flash services 55.9 after 56.5 is the growth tell into October odds
Earnings to Watch
A consumer week. Costco is the market-moving print.
- Tuesday: AutoZone before the open, about 54 dollars EPS on about 6.7 billion. Thor and MillerKnoll also before the open. KB Home after the close, the housing print after Lennar's miss.
- Wednesday before the open: General Mills about 0.72 dollars EPS. Cintas about 1.35 dollars and Paychex about 1.32 dollars. Cracker Barrel also reports.
- Thursday: Darden about 2.05 dollars EPS before the open. Costco after the close, about 6.53 dollars EPS on about 94.9 billion, at about 20:15 UTC. Comps and membership are the tell after Warsh's hike.
- Costco Thursday after the close, ~$6.53 EPS and ~$94.9B; membership and comps are the tell
- AutoZone Tuesday before the open, ~$54 EPS; KB Home after the close
- General Mills, Cintas, and Paychex Wednesday before the open
- Darden Thursday before the open; a consumer docket
Crypto Docket
Bitcoin is near 81,440 dollars (TradingView 81,368; CoinMarketCap 81,518), a hold above 80,000 after Friday's reclaim. Live levels: homepage. Avalanche Helicon Tuesday. Injective Meridian Thursday. Friday is Deribit quarterly bitcoin and ether options expiry. Plasma (XPL) unlocks about 152 million dollars Friday. Akedo unlocks about 109 million dollars Monday. No ETF decision deadline this week.
- Bitcoin ~$81,440, first hold above $80,000 since Sep 4 after last Tuesday's ~$74,910 low
- AVAX Helicon Tuesday; Injective Meridian Thursday
- Deribit quarterly BTC/ETH expiry Friday; XPL ~$152M unlock the same day
- No spot-ETF deadline this week; BTC bullish trigger: hold $80,000, then $82,000
How the Week Could Play Out
Three scenarios frame the docket, not a recommendation. In a trade-truce path, Thursday's readout extends the November 10 tariff pause and the S&P leans on Friday's 7,650.50 into Costco. In a hot-PMI path, a hold of August's 56.0 composite would keep October hike odds bid against a 5 percent 10-year. In a tariff-scare path, rare-earth or Taiwan language would reprice chips and the dollar first; Tokyo's first full session is Thursday. Traders watching 7,650.50 as the cash reference. Bullish trigger: a reclaim of 7,656.98, then 7,677.02. Bearish trigger: a slide through Friday's 7,610.52 low, then 7,551.81. For Bitcoin, a hold of 80,000 dollars then 82,000 is the bullish trigger; a slip through 75,000 is the bearish one. These are observations, not instructions.
- A truce extension Thursday would lean the tape on 7,650.50 into Costco and Friday durables
- A hold of the 56.0 composite would keep October odds bid; claims 204,000 after 196,000 is the labor test
- A rare-earth or Taiwan headline would hit chips and the dollar first; Tokyo's first print is Thursday
- S&P bullish trigger: reclaim 7,656.98 then 7,677.02; bearish: a slide through 7,610.52
ThriveInMarkets publishes market commentary for general information only and does not provide personal investment advice. S&P cash is Friday, September 18, 2026's close; E-mini futures and Bitcoin are live as of 06:00 UTC on September 21, 2026.