Nvidia earnings on Tuesday and the Fed minutes on Wednesday are the two events most likely to set the tone for stocks this week, as traders debate whether the Fed raises rates in December. For the background, catch up on last week here.
Prices as of Sunday evening. The S&P 500 closed Friday at 7,562 and Bitcoin trades near $64,500. All times are UTC.
- The Fed minutes on Wednesday show how many officials wanted to raise rates, which matters because traders now expect a hike.
- Nvidia reports its first results since its CEO left, and chip stocks have swung hard into the report.
- Retail sales and Walmart show whether shoppers are coping with higher prices and yields.
The Big One: Fed Minutes on Wednesday
The Fed held rates at 3.75% to 4.00% on 28 October by a 10 to 2 vote. After hotter inflation data, some investors now price a half-point hike for December. The minutes, due Wednesday at 19:00 UTC, show how wide that support was inside the Committee.
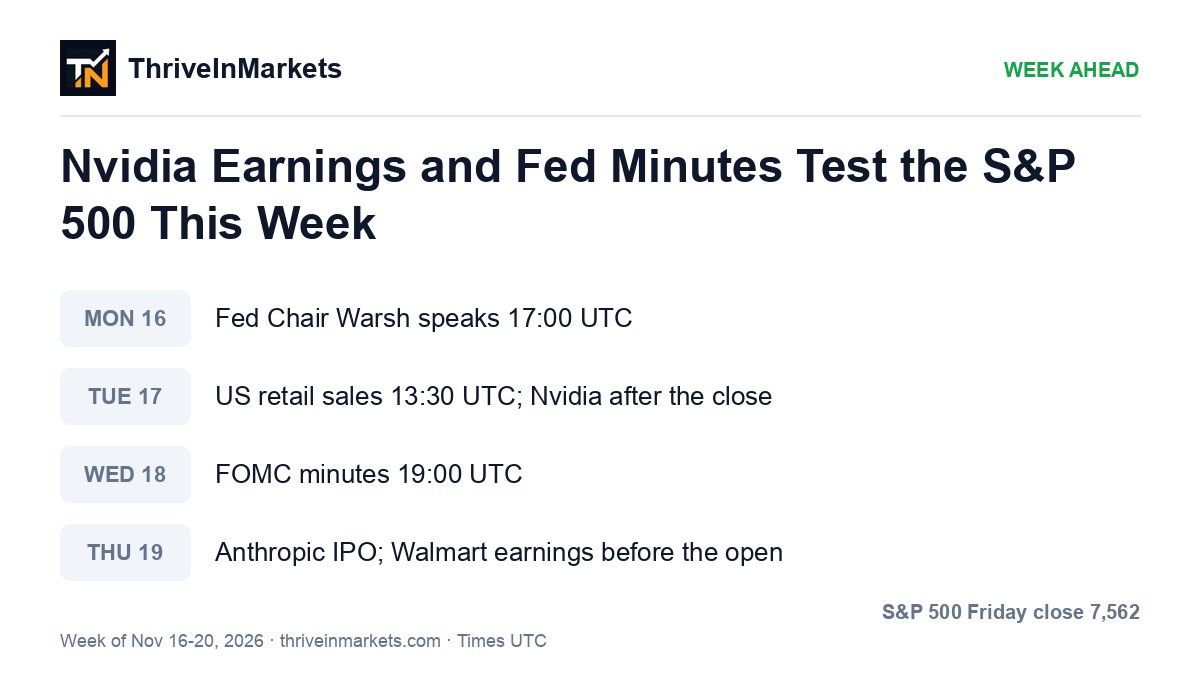
Fed Chair Kevin Warsh speaks on Monday at 17:00 UTC, and New York Fed President John Williams speaks at 14:05 UTC the same day. This is not a blackout week, so several officials can move rate expectations before the minutes arrive.
Scenarios to watch: hawkish language could extend the rise in the dollar and the 10-year yield, near 5.15%, while a patient tone could give gold and Bitcoin room to recover.
- Monday's Warsh speech sets the tone before the minutes.
- The wording on a faster pace of hikes is what traders will read first.
Economic Calendar
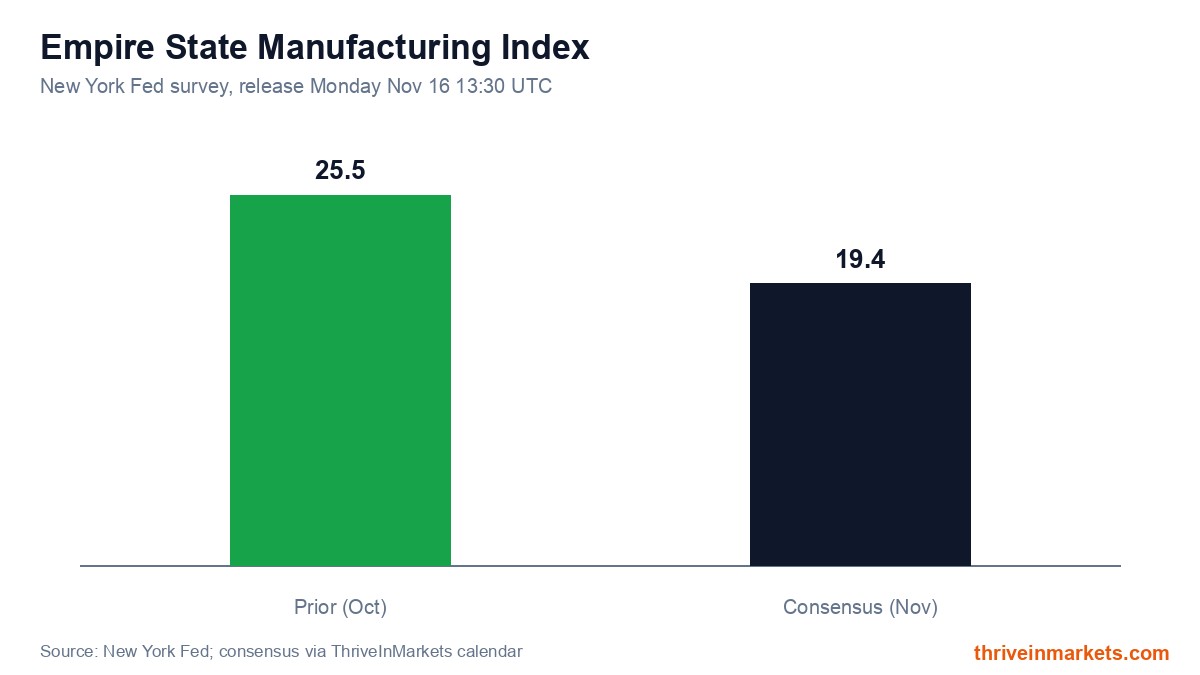
- Monday 16: China industrial production and retail sales (02:00), Canada CPI and the Empire State index (13:30, consensus 19.4 after 25.5), Williams (14:05), Warsh (17:00).
- Tuesday 17: UK jobs report (07:00), German ZEW survey (10:00), US retail sales (13:30, after +0.8% in September), industrial production (14:15).
- Wednesday 18: UK CPI (07:00, after 3.5% in September), US housing starts (13:30), EIA oil inventories (15:30), FOMC minutes (19:00).
- Thursday 19: Australia jobs (00:30), US jobless claims and the Philadelphia Fed index (13:30).
- Friday 20: China loan prime rate (01:30), UK retail sales (07:00), final Michigan sentiment (15:00, preliminary 51.0). It is also monthly options expiry.
- Tuesday carries the heaviest load: retail sales and Nvidia.
- A second strong retail sales print would back the case for a hike.
Earnings to Watch
- Nvidia, Tuesday after the close: analysts expect about $2.47 a share on roughly $109 billion of sales. The first report since Jensen Huang resigned.
- Home Depot and Disney, Tuesday before the open: a read on housing and travel spending.
- Lowe's and TJX, Wednesday before the open: more evidence on consumers before the holidays.
- Palo Alto Networks, Wednesday after the close: sets the tone for software stocks.
- Walmart, Thursday before the open: the cleanest read on household spending.
- Intuit, Thursday after the close: small business and consumer finance.
Anthropic is also expected to begin trading on the Nasdaq on Thursday, which could pull attention and money from other tech stocks.
- Guidance matters more than the headline beat at Nvidia.
- Walmart's holiday outlook reaches the whole retail sector.
Crypto Docket
Bitcoin slipped under $70,000 last week and sentiment is fragile. Token trackers show about $129 million of unlocks across 23 projects this week.
- Monday 16: Cronos (CRO) unlocks about 2.3% of its circulating supply, and Arbitrum (ARB) about 1.5%.
- Friday 20: LayerZero (ZRO) unlocks about 3.7% of its circulating supply.
Unlocks of this size rarely move Bitcoin alone, but new supply can weigh on the affected tokens. Crypto also reacts to the same Fed and Nvidia headlines as stocks.
- Unlocks hit the smaller tokens, not Bitcoin.
- The Fed minutes are the bigger driver for crypto this week.
How the Week Could Play Out
- Hawkish path: Warsh and the minutes back a faster hike, the dollar and yields rise, and stocks, gold and Bitcoin come under pressure.
- Calmer path: patient language and a solid Nvidia report lift chips and let yields ease, giving the S&P 500 room after its 2.5% weekly gain.
- Mixed path: strong retail sales but a weak Nvidia reaction leaves stocks split between a hike and AI worries.
Scenarios to watch: a break of the S&P 500's Friday close of 7,562 in either direction after Nvidia would show which path markets favour.
- Rates and AI are the two themes that decide the week.
- Friday's options expiry can add to moves in the final session.
This is market commentary for information only, not investment advice. ThriveInMarkets is based in Cyprus. Markets carry risk of loss.