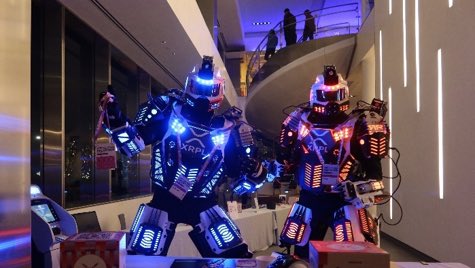
Source still from Mastercard's 16 November 2026 post on X: two LED robot costumes at an event venue, one marked XRPL.
XRP is the XRP Ledger's native asset. Banks can use it as a short currency bridge, but they don't have to. Mastercard's hackathon challenge settled in RLUSD, not XRP.
XRP exists to move value quickly on the XRP Ledger. In some payment products, it can sit briefly between two currencies so a bank does not have to keep as much cash prefunded in every corridor. That use is optional, and it only works where there is liquidity, and where the rules allow it. Price swings, custody and local regulation still matter.
That is the core design. The news that brought people here is narrower. On 16 November 2026 at 17:12 UTC, Mastercard posted on X about an XRP Ledger hackathon. The post links to a Mastercard story dated 3 November 2026. The event itself ran on 24 and 25 October 2026 in New York. It was a developer sandbox, not a decision by Mastercard to settle card payments in the XRP token, and not a bank-by-bank rollout. The settlement asset in that challenge was RLUSD, Ripple's dollar stablecoin.
What is XRP?
Four names often get treated as if they were the same thing. They are not.
- XRP is the native digital asset of the XRP Ledger. It is used to pay transaction fees, which are destroyed, and as a reserve so accounts and ledger objects are not free to spam. It can also be used as a bridge asset when one currency is exchanged for another. Its price is set in the market, so it can move around.
- The XRP Ledger, or XRPL, is the open-source public ledger, launched in 2012, on which XRP and issued tokens live. A payment can travel on this ledger without the customer-facing amount being denominated in XRP.
- Ripple is a technology company. It contributes software to the ledger, holds XRP, and sells products to institutions, including cross-border payments tools and a dollar stablecoin. Ripple is not the same thing as XRP, and it does not own the public ledger.
- RLUSD, or Ripple USD, is Ripple's US dollar-backed stablecoin. Ripple says each token is supported one-to-one by cash, US Treasuries and cash equivalents, and that it is issued under regulatory oversight. It is designed to stay near one US dollar. That is a different job from XRP.
Official XRPL documentation describes those three jobs for XRP in more detail. Fees paid in XRP are destroyed, which helps deter spam. Every account must hold a base reserve in XRP (on mainnet, currently 1 XRP). Even an account that only holds RLUSD still needs that base reserve. Extra ledger objects can add an owner reserve, currently 0.2 XRP each, but official docs say the first two trust lines can be created with just the base reserve if the account is funded with only that 1 XRP. And XRP can act as a bridge in the ledger's built-in exchange, automatically sitting between two issued tokens when that path is cheaper than a direct trade.
The ledger does not use mining, and it is not a proof-of-work chain like Bitcoin. Independent validator servers propose and confirm groups of transactions. Each server operator chooses a Unique Node List, or UNL: the validators it is willing to trust not to collude. Those servers go through short rounds of agreement until a supermajority is reached. Official XRPL docs say a valid ledger can usually be confirmed in a few seconds, typically about 3 to 5 seconds, and that confirming transactions "does not require wasteful or competitive use of resources, unlike most other blockchain systems."
The trust-list design is the tradeoff. Official docs say the network can keep moving if fewer than 20% of trusted validators are faulty, and that confirming an invalid transaction would require more than 80% of them to collude. If too many trusted validators fail or disagree, the network is designed to stall rather than split. Default UNL lists are published by parties that have included the XRP Ledger Foundation and Ripple; operators can choose a different list. How much influence those default lists have is a long-running debate, and it is one of the real limitations to weigh alongside the speed and energy claims.
Why might a bank use it?
Banks and payment firms already move money across borders every day. The usual plumbing often involves pre-funded accounts in local banks, called nostro accounts, plus several intermediaries. That can be slow, and it ties up cash in each corridor.
- A bank needs to pay someone in another currency.
- Instead of keeping a prefunded account in that country, it can, in supported corridors, buy XRP, send it, and sell it into the local currency.
- The beneficiary is paid in ordinary currency. The XRP is only a short-lived bridge.
- This depends on there being enough liquidity in that corridor. The bank still has to handle price moves, custody and local rules. It is not required to use XRP.
This is the design behind Ripple's On-Demand Liquidity product. Other Ripple or ledger flows can move value without using XRP as the payment asset.
Ripple's institutional payments docs describe two layers that are easy to blur. RippleNet is the company's messaging and settlement network for institutions. Using it does not, by itself, mean every payment is made in XRP. On-Demand Liquidity, or ODL, is the product that "uses the digital asset XRP as a bridge currency, sourcing liquidity on-demand, and moving funds in real time," and is pitched as a way to move value "without needing to pre-fund in any market."
In that ODL design, the sending institution typically starts in a local currency, XRP is bought and sent, then XRP is sold into the destination currency and paid out on local rails. The customer can be paid in ordinary currency. Official ODL onboarding notes say that, before payments start, Ripple will fund the sending institution's XRP wallet with a predetermined amount of XRP, and that this requires a Commit to Sell Agreement permitting the institution to hold XRP owned by Ripple. The institution still has to accept the operational, custody and market-liquidity requirements of using a traded asset as a short-lived bridge.
The limits are as important as the pitch. Liquidity is not the same in every corridor; ODL depends on exchange venues actually having enough XRP and local currency to complete both sides of the bridge. If the payment asset is XRP rather than a dollar stablecoin, price moves during the transfer, however short, are a real risk. Custody, key management and compliance still sit with the institution. Rules for digital assets and stablecoins also differ by country, so a setup that works in one place may not be available in another.
A bank or fintech might instead want the ledger's speed and 24-hour operation, but prefer a dollar token for the amount being settled. That is the role RLUSD is meant to play: ledger settlement with less price risk than holding or bridging through XRP. In the Mastercard hackathon challenge, that is the path that was specified.
So XRP can be required, optional, or unused as the payment asset, depending on the product:
- Required on the XRP Ledger for reserves and fees, even when the payment itself is in RLUSD or another issued token.
- Used as a bridge in On-Demand Liquidity and in some cross-currency paths on the ledger's exchange, in supported corridors.
- Not required as the settlement asset in the Mastercard hackathon challenge, which specified RLUSD, or in RippleNet flows that do not use ODL. Banks are not required to use XRP.
What did Mastercard test?
The event was the AI & Fintech XRP Ledger Hackathon, hosted by XRPL Commons at Apella in New York, the weekend before Ripple's Swell conference. Official partners and sponsors named by XRPL Commons were Ripple, Mastercard, AWS, Ledger, Quicknode and the XRP Ledger Foundation. Mastercard's story and post give the headline counts: 179 hackers and 70 submissions in 36 hours. XRPL Commons later said builders came from 20 countries, that about three in four projects were built around AI agents, and that 11 projects took 14 prizes. Mastercard wrote that contestants competed for more than $40,000 in prizes; the official event page lists $46,000 in total rewards.
Mastercard's 3 November story is specific about the challenge. Each team was asked to build an AI agent that could pay a verified merchant on its own, stay inside a predefined spending limit, and settle in RLUSD on the XRP Ledger.
The product in the middle of that flow is Mastercard Agent Pay for Machines, often shortened to AP4M. Mastercard launched it on 10 June 2026 as a way to credential AI agents, enforce spending rules, and settle high-frequency, low-value machine payments. Officially, settlement is multi-rail: cards, accounts and stablecoins. Ripple was listed among more than 30 initial participants and supporters in that June release, alongside firms such as Stripe, Coinbase, Cloudflare, Polygon, the Solana Foundation and OKX. This is not an XRP-only rail, and the June launch was not exclusive to the XRP Ledger.
- A person or business sets a spending limit and other rules for an AI agent.
- The agent needs to pay a merchant for a small service, such as data or model inference.
- Mastercard Agent Pay for Machines checks that the agent is credentialed, the payment stays inside the limit, and the merchant is verified.
- In this challenge, the payment was to settle in RLUSD on the XRP Ledger.
- If those checks pass, the merchant is paid.
Agent Pay for Machines can also settle across cards, bank accounts and other stablecoins. This challenge used RLUSD on the XRP Ledger. Some published team demos used test networks.
The Mastercard bounty went to a project called Wraps, described as an incognito mode for AI agents, with a $6,000 prize. Two other projects received early access to the Agent Pay for Machines payment facilitator. Other weekend projects used the ledger in different ways. XRPL Commons said RLUSD was the default dollar of the weekend and appeared in more than half of all projects. At least one prize-winning demo, Misa, locked XRP in native escrow as part of an x402 payment flow. That was a team design choice, not the settlement asset Mastercard set for its challenge.
Some published team write-ups describe demos on the XRPL EVM testnet and test-RLUSD, which have no real-world cash backing. Mastercard's own story does not say whether every challenge payment ran on mainnet. A weekend demo is not the same thing as live production volume. Turning a prize-winning prototype into a service that banks, merchants and regulators will trust takes longer, which XRPL Commons president David Bchiri also noted after the event.
This news does not show that Mastercard has started settling ordinary card transactions in XRP, or that banks must hold XRP to work with Mastercard, Ripple or the XRP Ledger. It also does not show a new exclusive Mastercard-XRP partnership. Agent Pay for Machines was already launched in June 2026 as a multi-rail service with a wide list of supporters. A successful RLUSD demo on the XRP Ledger does not mean other rails were discarded, or that XRP itself will be the asset those payments use.
Mastercard's story also repeats activity figures from Ripple Labs, including more than 500,000 daily AI-agent transactions on the XRP Ledger and more than 10 million payments over the x402 machine-payment protocol. Those numbers are Ripple's, as reported by Mastercard. They have not been independently checked here, and they should not be read as a forecast of token demand.
What to watch
- Whether institutions that want faster cross-border payments use an XRP bridge, a dollar token such as RLUSD, another rail, or none of them, and in which corridors the liquidity is actually there.
- Whether any hackathon project moves from a demo, including testnet demos, to a documented production integration.
- How Mastercard Agent Pay for Machines is actually used in live traffic, and on which settlement rails.
- Independent figures, not only company-reported ones, for agent payments and x402 activity on the XRP Ledger.
This article is for education and information only. It is not financial advice, and it is not a recommendation to buy, sell or hold XRP, RLUSD or any other asset.
Sources
- Mastercard on X, 16 November 2026, 17:12 UTC
- Mastercard, "36 hours to build trust in machine-driven commerce," 3 November 2026
- Mastercard, Agent Pay for Machines launch, 10 June 2026
- XRPL Commons, AI & Fintech XRP Ledger Hackathon event page (24-25 October 2026)
- XRPL Commons hackathon recap, 12 November 2026
- XRPL.org events, including Swell 2026 dates (27-29 October 2026)
- XRPL.org, XRP overview
- XRPL.org, Consensus protocol
- XRPL.org, Consensus principles and rules
- XRPL.org, Reserves
- XRPL.org, Cross-currency payments
- Ripple, RLUSD product page
- Ripple docs, What is RLUSD?
- Ripple docs, RippleNet and On-Demand Liquidity
- Ripple docs, Using On-Demand Liquidity