The week of October 12 to October 18, 2026 was a chip crash, a CoreWeave credit scare, and an oil spike that put Brent back at 110 dollars. South Korea's Kospi tripped circuit breakers on Thursday. The Nasdaq Composite closed Friday at 26,140.03, down 4.5 percent on the week, its worst week since June (Associated Press / Seattle Times). The S&P 500 closed Friday at 7,659.44, down 1.9 percent from 7,811.54. WTI's Friday NYMEX settlement was 101.41 dollars, up 10.4 percent. Bitcoin last printed about 81,576 live on Sunday. Traditional markets are closed. Stock, gold and oil figures are Friday's closes (October 16). US cash reopens Monday. See Saturday's weekly markets roundup.
Weekly Scorecard: Nasdaq's Worst Week Since June
Monday opened on Columbus Day, bonds shut and cash open. Wednesday's 3.7 percent CPI print cut the S&P 1.11 percent to 7,718.94. Thursday repaired to 7,744.06. Friday gave it back. At Friday's cash close the S&P 500 stood at 7,659.44, down 1.1 percent on the day and down 1.9 percent on the week from 7,811.54 (Associated Press, FRED, YCharts). Friday range 7,631.77 to 7,756.84. October 6's 7,818.93 record close remains unrepaired. The Nasdaq Composite finished at 26,140.03, down 4.5 percent on the week. The Dow closed at 52,002.41, up 0.7 percent. Those equity figures are Friday closes. Catch up: Friday's evening review.
- S&P 500 -1.9% on the week to a Friday close of 7,659.44, after a 1.1% Friday drop
- Nasdaq -4.5% at 26,140.03, worst week since June; Dow +0.7% at 52,002.41
- Oct 6 record close 7,818.93 unrepaired; Friday range 7,631.77-7,756.84
- All equity figures are Friday closes (October 16); cash reopens Monday
Biggest Movers of the Week
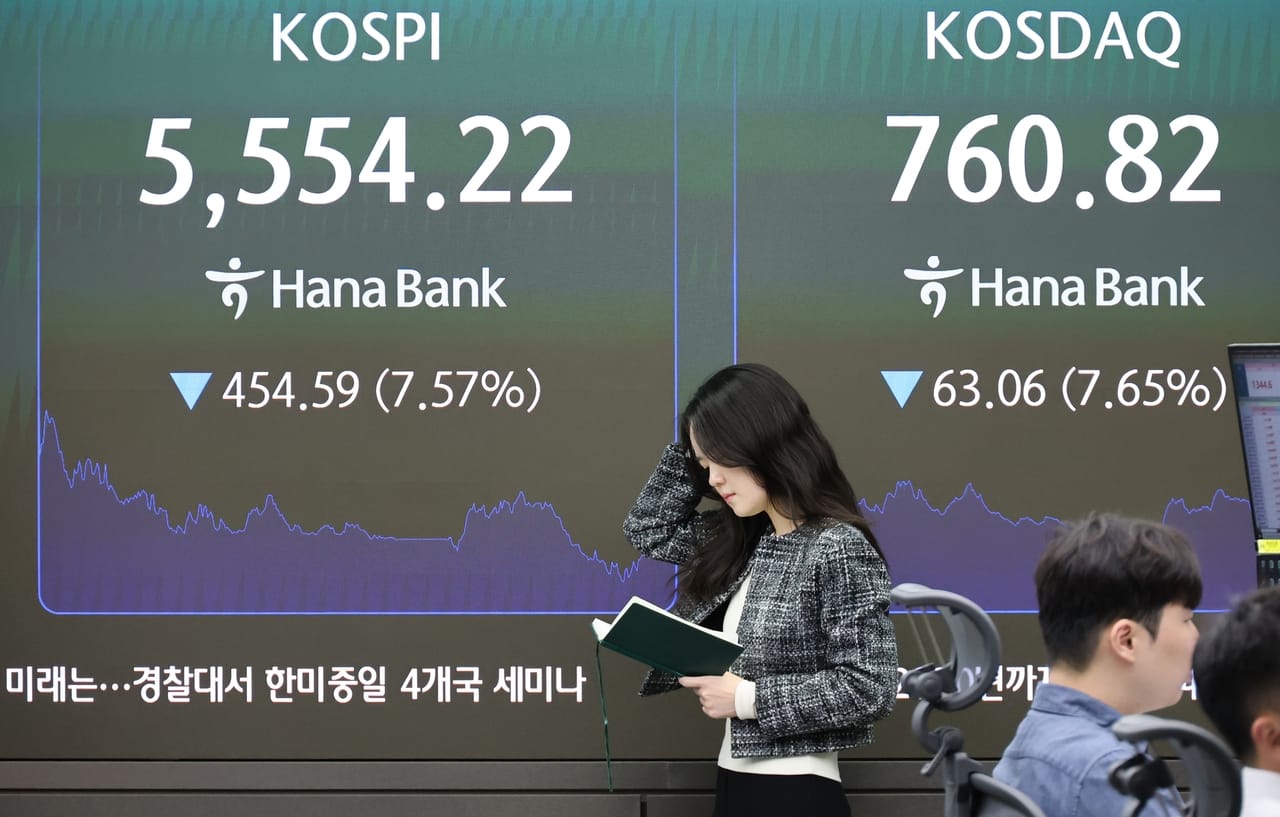
Tuesday opened the Seoul slide after China's ChangXin Memory Technologies advanced a denser DRAM design. The Kospi closed 6,035.35, down 5.5 percent (Tuesday's note). Thursday was the crash. The Kospi closed 5,554.22, down 7.57 percent, tagged 5,450.81, and halted at 12:38 p.m. local, the first circuit breaker since July 29 (Korea Herald). Samsung fell 9.48 percent. SK hynix fell 11.06 percent. Foreigners sold 3.62 trillion won. Benzinga put the Kospi at down 14.46 percent on the week, its steepest weekly drop since October 2008, with Samsung down 17.8 percent Monday to Friday and SK hynix down 24.3 percent. Friday snapped a seven-session losing streak: the Kospi closed 5,668.05, up 2.05 percent (Yonhap). Nvidia closed Friday at 214.70 dollars.
CoreWeave became the listed proxy for AI-buildout leverage. Unsecured 2032 yields tagged about 15 percent and CDS printed near 1,000 basis points (Reuters) against about 50 billion dollars of debt. Shares closed Friday at 61.39 dollars, down 11.91 percent, more than 25 percent below last Friday's 82.08. Goldman Sachs posted EPS of 17.01 dollars versus about 13.02. JPMorgan missed at 5.57 dollars versus about 5.90. Bank of America took a 1.2 billion dollar penalty. TSMC still printed a sixth straight record quarter. The listed chip beta sold the financing risk anyway.
- Kospi Thursday 5,554.22 (-7.57%), circuit breaker; week about -14.5% worst since 2008; Friday 5,668.05 (+2.05%)
- Samsung week -17.8%; SK hynix week -24.3%; Nvidia Friday $214.70
- CoreWeave Friday $61.39 (-11.91%); 2032 bonds ~15% yield; CEO sales nearly $1B since IPO
- Goldman EPS $17.01; JPM miss $5.57 vs $5.90; BAC $1.2B fine; TSMC NI +69%
Macro: Hot CPI, Hotter PPI, Then Warsh Holds Fire
Wednesday's September CPI was the last major inflation print before the October 27-28 FOMC. Headline rose 0.6 percent on the month and 3.7 percent year over year (Reuters). Core rose 0.3 percent and 2.6 percent. Gasoline jumped 9.1 percent on the month. Thursday's PPI printed 1.3 percent month on month, the largest since March 2022, and 6.3 percent year over year. Retail sales rose 0.8 percent; the control group printed 0.1 percent.
Friday, Chair Kevin Warsh told the IMF meetings in Bangkok he does not prejudge meetings and offered no path for October 27-28. The Straits Times said October hike odds fell from about 27 percent to below 15 percent after (Friday's note). The Fed entered communications blackout on Saturday. Industrial production printed 0.7 percent. Gasoline is already inside CPI and PPI.
- September CPI +0.6% / +3.7%; core +0.3% / +2.6%; gasoline +9.1% m/m
- PPI +1.3% m/m, largest since March 2022, +6.3% y/y; retail +0.8%, control +0.1%
- Warsh offered no October path; hike odds ~27% to below 15%; blackout started Saturday
- FOMC still October 27-28
Oil and Geopolitics: WTI Settles $101.41 After a $110 Brent Tag
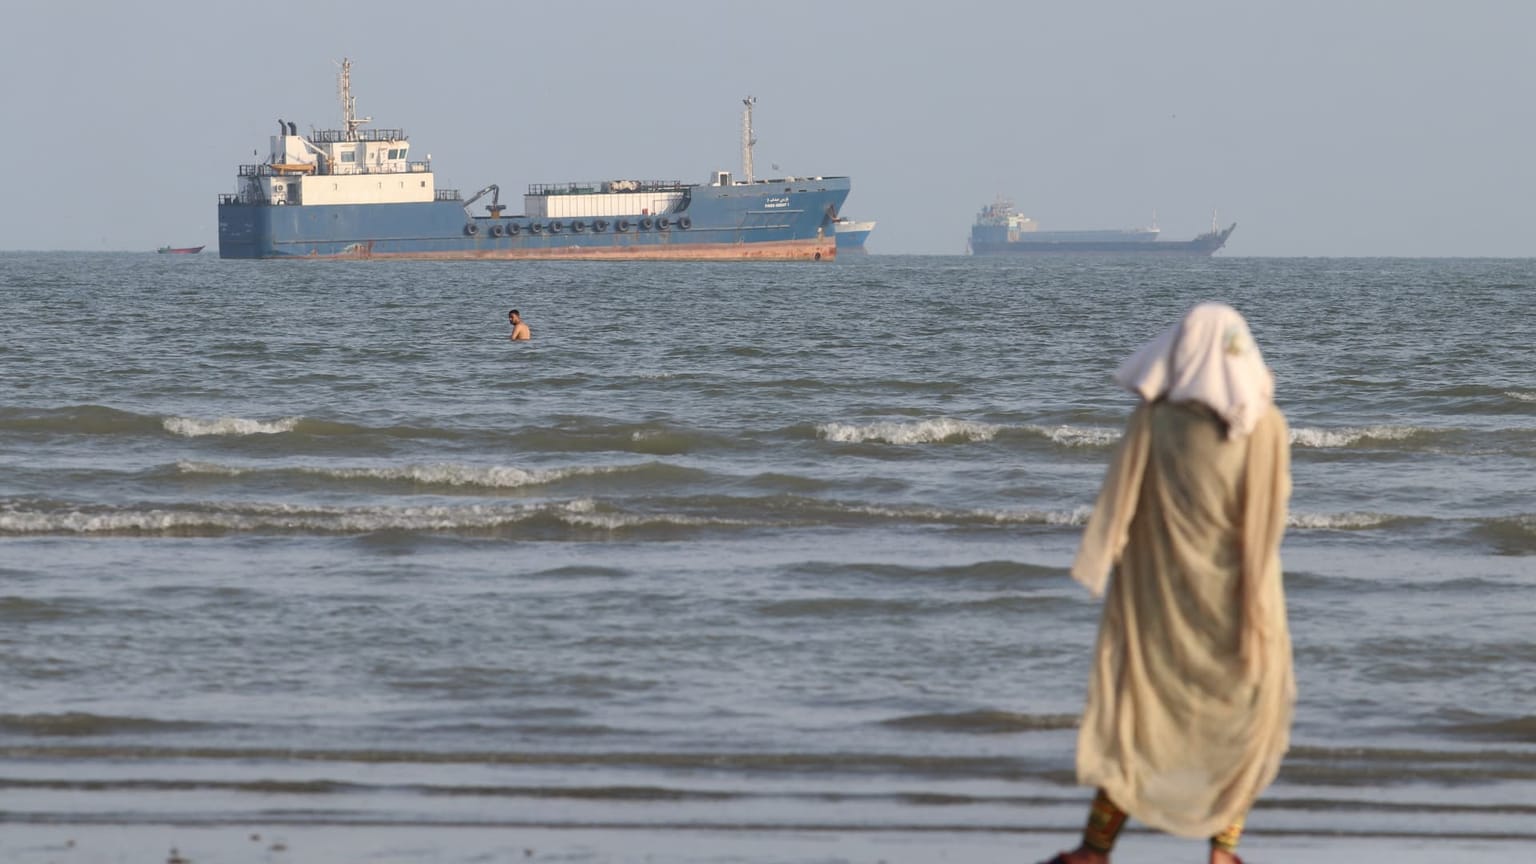
Oil was the week's biggest asset move. Trump's claimed Russia-Ukraine energy truce did not hold. Ukraine struck Russian refineries. Iran stepped up Hormuz attacks; CNBC counted at least nine commercial ships hit since Sunday. Kpler put Hormuz crude flows near 9.4 million barrels a day, about 70 percent of the pre-war average. The IEA agreed to release more than 20 million barrels of diesel. WTI still settled Friday at 101.41 dollars (MarketWatch, Investing.com, CNBC), up 10.4 percent on the week from last Friday's 91.85. Range 96.85 to 101.90. Brent settled 109.86 dollars after tagging 110, the first time since May. Spot gold closed Friday about 4,165 dollars (GoldPrice.com 4,165.42; MarketScreener 4,165.18), down about 0.7 percent from last Friday's 4,195. Wednesday's floor near 4,066 still holds. Gold and oil figures are Friday closes. Those markets reopen with electronic hours Sunday evening, then a full session Monday.
- WTI $101.41 (Friday settlement), week +10.4% from $91.85; range $96.85-$101.90
- Brent Friday $109.86 after a $110 tag, first since May; Hormuz flows ~9.4 mbpd
- IEA extra 20 million barrels did not cap the Friday squeeze
- Gold $4,165 (Friday close), about -0.7% on the week; Wednesday floor near $4,066
Crypto: Bitcoin Holds $81,576 After a $611 Million ETF Bleed
Bitcoin is near 81,576 dollars live on Sunday (TradingView 81,576; CoinMarketCap about 81,559 to 81,622), down about 1.6 percent from last Sunday's 82,936. Monday's about 84,032 was the week's high. Thursday's low sat near 79,800. Ether holds near 2,406 dollars live (TradingView 2,406.3), down about 3.7 percent from last Sunday's 2,498. Those are 24/7 prints as of 09:05 UTC. Live levels sit on the ThriveInMarkets homepage.
US spot crypto ETFs lost 610.7 million dollars from October 12 to 16 (crypto.news / Farside). Ether funds lost 320.1 million, overtaking Bitcoin's 228.4 million. Solana products lost 25.5 million every session, an 11-session October streak. On Monday Ripple-backed Evernorth began Nasdaq trading as XRPN (Decrypt) with about 473 million XRP. About 80.3 percent of Armada holders redeemed. XRPN opened at 16.68 dollars. BTC bullish trigger: a reclaim of 82,286 dollars, then about 82,717. Bearish trigger: a slip through about 80,735, then Thursday's 79,800 low.
- Bitcoin ~$81,576 (live), down ~1.6% from last Sunday; Thursday low ~$79,800; spot BTC ETFs -$228.4M Oct 12-16
- Ether ~$2,406 (live), about -3.7% from last Sunday; Ether ETFs -$320.1M, larger than Bitcoin
- SOL ETFs -$25.5M every session, 11-day October streak; five-table total -$610.7M
- XRPN Nasdaq debut Monday; 473M XRP; opened $16.68; 80.3% SPAC redemptions
The Week Ahead: Netflix, Tesla, Meta, Then Flash PMIs
Cash reopens Monday. Gold and oil resume electronic hours Sunday evening. Crypto still trades. The Fed is silent through the October 27-28 FOMC. These are scenarios for next week, not instructions. Docket: calendar.
- Tuesday, October 20: Housing starts at 12:30 UTC. GM before the open. Netflix after the close, consensus EPS about 0.82 dollars.
- Wednesday, October 21: Tesla and Meta after the close. Tesla already reported 486,532 third-quarter deliveries. Texas Instruments and Lam Research the same afternoon. Solana's Alpenglow upgrade is expected around this date.
- Thursday, October 22: Procter & Gamble before the open. Weekly claims at 12:30 UTC. Leading index at 14:00 UTC.
- Friday, October 23: Flash manufacturing and services PMIs. Michigan final after the preliminary 46.3. American Express before the open. Then FOMC October 27-28.
Traders watching 7,659.44 as the cash reference. Bullish trigger: a reclaim of Friday's 7,669.66 then Thursday's 7,744.06. Bearish trigger: a slide through Friday's 7,631.77 low. These are observations of the price structure, not instructions.
- Tuesday: housing starts; GM; Netflix after the close, seen ~$0.82
- Wednesday: Tesla, Meta, TXN, LRCX after the close; Solana Alpenglow ~October 21
- Friday: flash PMIs; Michigan final; AXP; FOMC still October 27-28
- S&P bullish trigger: reclaim 7,669.66 then 7,744.06; bearish: 7,631.77. Cash reopens Monday
ThriveInMarkets publishes market commentary for general information only and does not provide personal investment advice. Equity, gold and WTI figures are Friday closes for October 16, 2026. Equities reopen Monday. Bitcoin and Ether are live as of 09:05 UTC on October 18, 2026. Levels cited are observations, not instructions to buy or sell any asset.